
⚡ Interactive Tax-Optimization Tool
Mega Backdoor Roth Contribution Calculator
Determine your exact remaining after-tax 401(k) space for a Mega Backdoor Roth conversion after accounting for employee deferrals, employer matches, and IRS compensation limits.
🧮 Enter Your 401(k) Plan Details
Updated with official IRS 2026 contribution limits (Section 415(c) & Section 401(a)(17)).
Your 401(k) Breakdown
Total Cap: $71,000
Available After-Tax Contribution Room
$41,600
Eligible for Mega Backdoor Roth Conversion
Section 415(c) Bucket Allocation $71,000 Max
1. Elective (34%) 2. Match (8%) 3. After-Tax (58%)
IRS Overall Limit (Sec. 415c):
$71,000
(-) Employee Deferral:
-$24,000
(-) Employer Match:
50% on first 6% of $180,000
-$5,400
(=) Remaining Mega Backdoor Space:
$41,600
🗓️ Per-Paycheck Allocation
Payroll Deductions
To hit your maximum after-tax limit evenly throughout the tax year without under-contributing or front-loading, set your payroll deduction to:
Bi-Weekly (26 Paychecks/yr)
$1,600.00
every 2 weeks
Semi-Monthly (24 Paychecks/yr)
$1,733.33
twice per month (15th & 30th)
💡 True-Up Tip: If your company offers a 401(k) true-up provision, you can max out earlier in the year without forfeiting your employer match.
Was this calculation helpful?
📬
Email My Mega Backdoor Roth Plan (includes the free newsletter)
Did you mean ? Click to fix.
✉ No spam. Unsubscribe anytime with 1 click.
How the 2026 Mega Backdoor Roth Contribution Limits Work
The Mega Backdoor Roth strategy allows high-income earners to exceed the standard $24,000 elective deferral limit and contribute up to the total IRS Section 415(c) limit ($71,000 for under age 50 in 2026) into tax-free Roth accounts.
TL;DR Calculation Formulas: Maximum After-Tax 401(k) Space
Maximum After-Tax Capacity = Section 415(c) Limit - Employee Elective Deferrals - Employer Match
Eligible Employer Match Base = Min(Annual Salary, Section 401(a)(17) Compensation Cap)
Per-Paycheck Contribution Target = Maximum After-Tax Capacity / Remaining Pay Periods in Tax Year
🏛️ IRS Section 401(a)(17) Salary Cap
Even if your compensation is $500,000, federal law caps the maximum salary recognized for 401(k) matching at $355,000 in 2026. Any percentage match formula only calculates up to this ceiling.
🔄 Automatic In-Plan Conversions
After making voluntary after-tax contributions, you must immediately convert them to a Roth 401(k) or Roth IRA. Doing this automatically prevents earnings from growing in a taxable pre-tax bucket.
📥 Free Printable PDF Guide 1-Page Printable PDF
Download the Mega Backdoor Roth Decision Tree (PDF)
Plan compliance checklist and 401(k) waterfall verification flowchart. Keep on hand when reviewing plan summary documents or speaking with HR.
- ✓ Clean, 1-page printable reference cheat sheet
- ✓ Instant direct access and email delivery
- ✓ Updated with current statutory limits & guidelines
✓
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this checklist handy for retirement and tax planning!
Mobile Handoff
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
🔖
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Your Next Step & Related Guides
View all resources
Step-by-Step Guide
Featured Tool
Backdoor Roth IRA with Fidelity
A walkthrough of the two-step backdoor Roth process.
Open Guide
Mega Backdoor Roth • • ⏱ 12 min read
What's A Mega Backdoor Roth?
If you like your Roth IRA for its tax-free growth, you’re really going to like a mega backdoor Roth! Contributions to a Roth IRA are funded with after-tax dollars and earnings grow
Read guide
Backdoor Roth • • ⏱ 6 min read
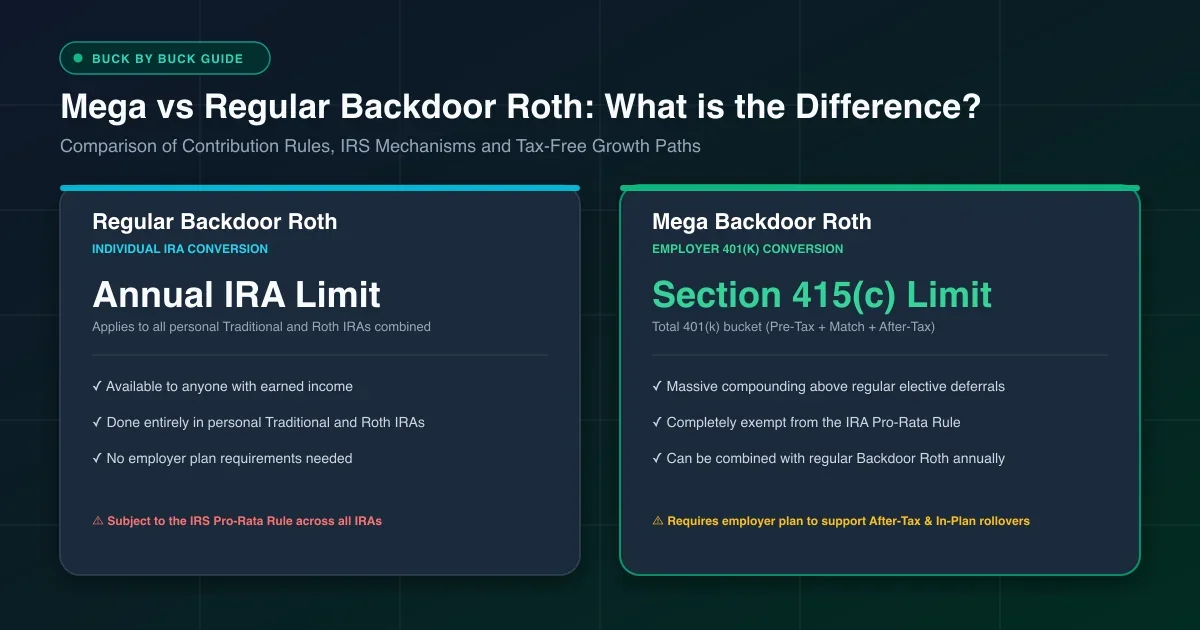
Mega vs Regular Backdoor Roth: What's the Difference?
For high income earners, the Backdoor Roth conversion is a popular way to get around the income limits that prevent high earners from contributing directly to a Roth IRA. The Mega
Read guide
Discussion 0
Author replies within 24h