
⚡ Interactive Audit + Reader Case Study Board
Synced to 2026 IRS Statutory Limits
🔒 100% Client-Side & Anonymous
FI & Tax Blind-Spot Scorecard & Anonymous Case Study Review Board
Benchmark your balance sheet, savings velocity, and retirement horizon against 2026 IRS limits in 60 seconds. Uncover hidden tax drag, idle cash leaks, RSU Restricted Stock Units granted by an employer that vest into company shares and are taxed as ordinary W-2 income upon vesting. concentration risk, and trapped ROE Return on Equity: annual net cash flow or appreciation divided by the liquid net equity tied up in a property. . Save a printable 1-page scorecard or post your anonymized snapshot below for an official educational breakdown from the author.
For general educational modeling only. Not individualized investment, legal, or CPA advice. Full Disclaimer.
⚡ Load a Sample High-Earner Archetype (Or Enter Your Own Numbers Below)
Click any preset to see how the 6-pillar blind-spot engine scores real-world trade-offs:
1. Your Anonymized Snapshot
Live Auto-ScoreA. Household, Timeline & Cash Flow
B. 2026 Tax Shelter Utilization
Annual Additions This Year
1. Employee 401(k) / 403(b)
Base limit: $24,000
2. Roth / Backdoor IRA
Cap: $7,500/person ($15,000 MFJ)
3. Health Savings Account (HSA)
Cap: $4,400 single / $8,750 family
4. Mega Backdoor Roth (After-Tax 401k)
Total plan limit: $71,000
C. Current Account Balances Today
Total Accumulated (Not Annual Additions)Enter current account balances accumulated to date across your portfolios (do not enter this year's annual contributions):
D. Real Estate Equity & High-APR Debt
Buck by Buck Quantitative Diagnostic (2026 Rules)
Wealth & Tax Optimization Scorecard
Calculating your savings velocity, tax triangle, and blind spots...
Overall Score
82 /100
Grade: B+
FI Progress: 28%
Savings Rate 26.6% Target: 25%+
Liquid Portfolio $905K Goal: $2.88M
Retirement Horizon Age 50 Pace: 109% of Goal
Est. Annual Leak $4,850/yr Recoverable Drag
6-Pillar Quantitative Breakdown
Weighted out of 100 pts✅ What Is Working Well (Pros)
⚠️ Mathematical Blind Spots (Cons)
Step 2 · Author & Community Review
Want the Author to Review Your Anonymous Snapshot?
1-click formats your anonymized numbers into the review board below. Enter your optional private email to get 1 alert when the author posts an educational breakdown or turns your scenario into a featured blog post.
📄 Save or Print Your 1-Page Scorecard PDF + Weekly Wealth Insights
Enter your email to unlock instant 1-page PDF printing and join our free high-earner newsletter (or copy your anonymized link):
🧭 Mathematical Scenarios & Deep-Dive Calculators to Explore Next
Custom scenario modeling based on your balance sheet inputs:
2. Public Reader Case Study & Author Review Board
Browse anonymized snapshots from other high earners, share a perspective, or post your own scorecard above. Verified author replies carry the ⚡ Official Author Breakdown badge, and top submissions are selected for full Reader Case Study articles.
How the 6-Pillar Wealth & Tax Blind-Spot Model Works (2026 Edition)
High-income households frequently earn $250,000 to $600,000+ yet lose $5,000 to $25,000 per year to silent structural leaks. Our diagnostic engine audits your numbers across six mathematical equations automatically synchronized to the 2026 IRS tax code:
1. Savings Velocity & FI Runway (25 Points)
Measures total annual additions against gross household income and calculates your liquid 25x Financial Independence target (4.0% initial benchmark) and early retirement runway.
2. 2026 Tax Shelter Capture (25 Points)
Verifies whether you are capturing the $24,000 employee 401(k) limit ($32,000 age 50+, $35,250 ages 60 to 63), $7,500 Backdoor Roth IRA, $8,750 family HSA, and $71,000 total addition Mega Backdoor Roth.
3. 3-Bucket Tax Triangle Balance (15 Points)
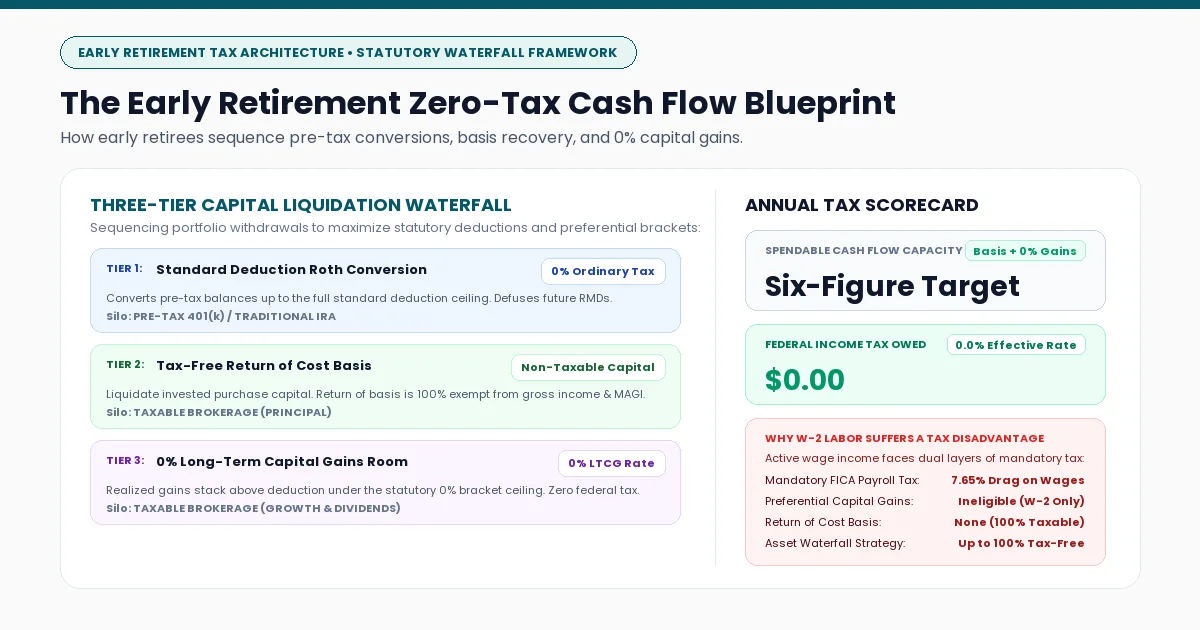
High earners who hold 85%+ of net worth in pre-tax 401(k)s face required minimum distribution tax bombs and pre-59.5 lockup. Balancing Taxable, Roth, and Pre-Tax buckets unlocks $0 federal tax early retirement ($32,200 MFJ standard deduction + $96,700 0% LTCG ceiling).
4. Cash Drag & State-Tax-Exempt Treasury Yield (10 Points)
Holding more than 6 to 12 months of living expenses in bank checking or state-taxable HYSAs creates unnecessary drag. Shifting core reserves into a Rolling Treasury Bill Ladder exempts interest from state and local income taxes.
5. Single-Stock & ETF Overlap Risk (15 Points)
Unvested and vested employer equity (Amazon RSUs, Netflix SOP) or overlapping tech ETFs (ETF Overlap Screener) above 10% of liquid net worth introduces uncompensated idiosyncratic risk.
6. Trapped Home Equity ROE & Debt (10 Points)
Keeping a former primary residence as an accidental rental often yields 2% to 3% Return on Equity while risking the $500,000 tax-free primary home sale exclusion. Compare yours in the Real Estate Evaluation Tool.
Frequently Asked Questions
Is my financial data stored anywhere when I use the calculator? ▼
No. All scorecard math runs locally in your browser. Nothing is transmitted to our servers unless you voluntarily click the button to submit an anonymized snapshot to the public Community Case Study Review Board.
How do you prevent spam if I include my email on a Case Study submission? ▼
Your email address is never displayed publicly. Community members cannot trigger emails to you. Our backend enforces a strict one-email-per-submission lock that sends you a single notification only when the verified Buck by Buck author posts an official educational breakdown on your thread.
Does this scorecard or an author review replace a CPA or fiduciary advisor? ▼
No. Buck by Buck is an educational financial publication operating under the publisher exclusion for impersonal financial education. All scorecard outputs and case study discussions illustrate general mathematical principles and tax rules for our readership at large. Always verify your specific situation with a licensed CPA, attorney, or fee-only fiduciary advisor.
📬
Offline Reference
Save This to Your Inbox
Enter your email and we'll send you this article as a formatted reference guide, plus subscribe you to the free Buck by Buck newsletter.
Did you mean ? Click to fix.
✉ No spam. Unsubscribe anytime with 1 click.
Was this calculation helpful?
Mobile Handoff
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
🔖
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Your Next Step & Related Guides
View all resources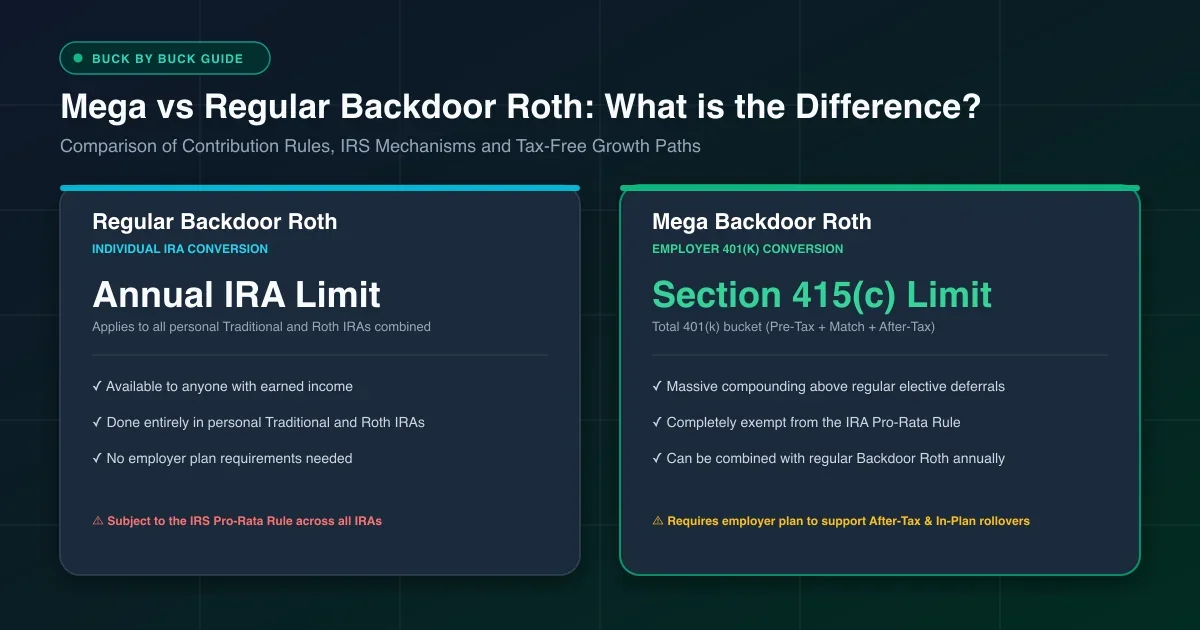
Free Tool
Featured Tool
Mega Backdoor Roth Calculator
Estimate your remaining after-tax 401(k) contribution space.
Launch Tool
Retirement • • ⏱ 19 min read
How Early Retirees Live on Six Figures Tax-Free with $0 in Federal Income Tax
Discover how early retirees engineer six-figure spendable cash flow while paying $0 in federal income tax using the strategic tax waterfall strategy.
Read guide
Real Estate • • ⏱ 8 min read
Risks and Tradeoffs of Real Estate Investing
In my past post, 6 Reasons Why I Invest In Real Estate to Build Wealth, I talked about the many benefits of investing in real estate. However, it’s important to highlight the risks
Read guide
Reader Case Study Submissions & Author Breakdowns 🟢 Open for Discussion 0