Best Firms to Borrow Against Stocks: Lowest Margin Rates, IBKR Pro, Robinhood Gold & Box Spreads (Part 2)
Portfolio Borrowing Series: Firm Comparison, Real Rates & Spending Flexibility
Need the fundamental concepts first? Start with Part 1: How to Borrow Against Your Stocks at Lower Rates Than a Mortgage (SBLOC vs. Margin Guide) →
In Part 1 of this guide, we walked through the basics of borrowing against your taxable stock portfolio: how it gives you cash without selling shares, skips a painful capital gains tax bill, avoids mortgage closing costs, and stays safe as long as you keep your Loan-to-Value (LTV) ratio under 25% to 35%.
Now for the practical question that actually saves you real money: Which brokerage gives you the lowest interest rate, and which ones actually let you pull cash out for real estate, home renovations, taxes, or personal spending?
If you just log into a typical brokerage account and borrow on margin, you'll probably get hit with retail interest rates between 11% and 13.5%+. That makes no sense when the base rate is around 3.88%. If you know where to look, or how to negotiate, you can easily borrow in the 4.3% to 5.5% range instead. Here’s a straightforward breakdown of how the top firms stack up, what they actually charge (as of late 2026), their withdrawal rules, and an options technique (box spreads) that lets you lock in fixed rates even lower.
How Borrowing Rates Are Actually Calculated
Almost every floating-rate portfolio loan in the US, whether it's margin or a Securities-Backed Line of Credit (SBLOC), uses a simple formula:
As of late 2026, the Secured Overnight Financing Rate (SOFR) ↗ sits around 3.88%. The difference between an absurd 11% to 12% margin rate and a reasonable 4.88% rate comes down entirely to how much markup your broker tacks on:
- Standard retail brokerages: Often add an extra 6.0% to 8.5% markup for regular accounts, leaving you with an 11% to 13.5%+ rate.
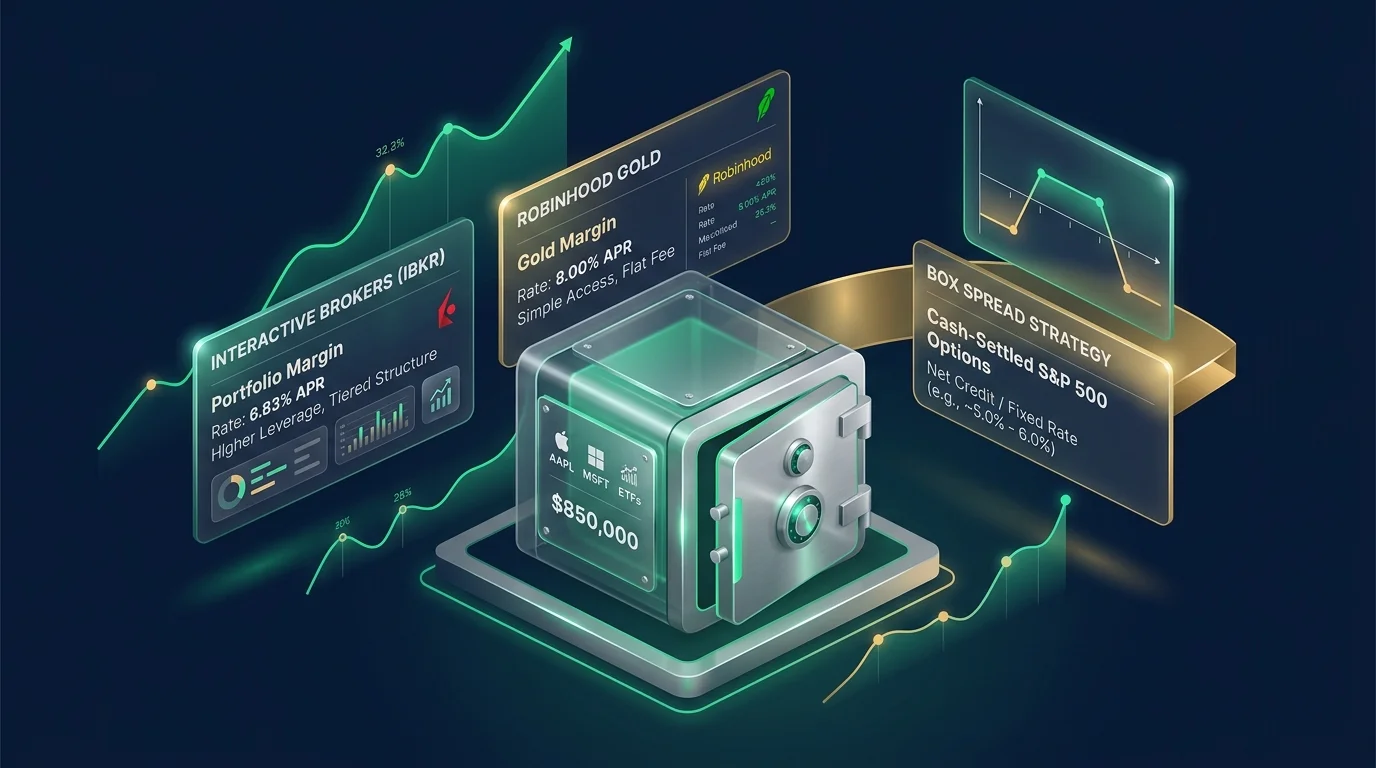
- Robinhood Gold ↗: Offers tiered rates starting with the first $1,000 interest-free, followed by 5.25% up to $50k, 5.05% up to $100k, 4.75% up to $1M, and 4.50% for balances over $1M.
- Interactive Brokers (IBKR Pro) ↗: Uses transparent, tiered markups between 0.50% and 1.5% with no bartering needed.
- Traditional brokers (Fidelity, E*TRADE, Schwab): Their published rates are high, but if you have $500,000+ in assets, you can call their private wealth desks to negotiate a custom rate down to SOFR + 1.0% to 1.75%.
- Box Spreads: An options trade that lets you borrow directly against Treasury rates (tracked live on BoxTrades.com ↗), locking in roughly 4.1% to 4.4% fixed.
Can You Actually Pull the Cash Out?
Before you pick a broker, there’s an important detail you need to check: how easy is it to actually withdraw cash?
In a brokerage account, there are two completely different kinds of borrowing power:
- Buying power: The ability to buy more shares inside your account using margin. Basically every margin account lets you do this automatically.
- Withdrawable cash: Actual dollars you can transfer to your checking account, wire to a real estate escrow company, or spend with a debit card.
Some brokerages only let you use margin to trade stocks. If you want cash in hand, you have to open a separate credit line (like an SBLOC). Others let you borrow and transfer cash right out of your existing account. Here is a side-by-side look at how the main options compare.
Comparing Margin & Borrowing Rates Across Brokers
Rates below are estimates as of late 2026 based on a benchmark SOFR of 3.88%. Floating rates adjust in tandem with Federal Reserve interest rate moves.
| Broker / Strategy | Estimated Rate & Spread | Cash Access | Margin Call Policy | Best For |
|---|---|---|---|---|
| Interactive Brokers (IBKR Pro) |
4.38% to 5.38%
SOFR + 0.50% to 1.50%
|
ACH transfer or domestic wire |
Instant auto-liquidation
No calls, shares sold automatically
|
Portfolios > $100k wanting low, automated rates |
| Robinhood Gold |
4.50% to 5.25%
0% on first $1k; balance tiered
|
Transfer to bank or debit card |
24-hr deposit window
In-app alerts before liquidation
|
Portfolios under $250k wanting simple, low-cost cash |
| Fidelity (Private Client / SBLOC) |
4.88% to 5.38%
SOFR + 1.0% to 1.5% ($500k+)
|
Separate line, checkbook, or wire |
2 to 5 business days
Personal wealth advisor outreach
|
Accounts with $500k+ wanting personal customer service |
| E*TRADE (Morgan Stanley) |
4.88% to 5.38%
Negotiated SBLOC facility
|
Dedicated credit line, checks, wires |
Grace period with advisor
Private banker contact window
|
E*TRADE clients looking to fund real estate or large expenses |
| Charles Schwab (PAL) |
4.90% to 5.50%
Pledged Asset Line spread
|
Dedicated credit line, checks, wires |
Multi-day cure period
Banker calls before asset sale
|
Schwab clients who want a dedicated credit facility |
| Box Spread (SPX) |
4.10% to 4.40% FIXED
Near Treasury curve
|
Transfer net credit via ACH or wire |
Settles at expiration only
No early assignment risk (European)
|
Experienced investors wanting fixed multi-year sub-5% money |
Input your portfolio size and loan balance to calculate monthly interest and crash safety buffers in real time.
1. Interactive Brokers (IBKR Pro): The Best Automated Rates
Interactive Brokers is popular in the FIRE community for good reason: they don't play games with their margin rates. You don't have to call up a private banker, negotiate, or meet massive asset minimums to get a fair rate. Their tiered rates are posted transparently on the IBKR margin schedule ↗.
| Borrowing Amount | Spread over Benchmark | Approximate Total APR (As of Late 2026) |
|---|---|---|
| First $100,000 | Benchmark + 1.50% | ~5.38% |
| $100,000 to $1,000,000 | Benchmark + 1.00% | ~4.88% |
| $1,000,000 to $3,000,000 | Benchmark + 0.75% | ~4.63% |
| $3,000,000+ | Benchmark + 0.50% | ~4.38% |
Pulling cash out of IBKR is dead simple. As long as you have excess borrowing power, you can initiate an ACH transfer or wire straight to your personal checking account (or to an escrow title company for real estate). Your loan balance increases automatically, and interest accrues daily at your effective rate tier.
2. Robinhood Gold: The Best Low-Balance Tiers for Accounts Under $250k
If your portfolio is under $250,000, traditional brokerages will charge you an absurd 12% to 13.5% in margin interest. Robinhood changed the game by offering competitive borrowing rates through Robinhood Gold ↗, using a tiered rate structure based on your total settled margin balance.
| Settled Margin Balance | Robinhood Gold Margin Rate |
|---|---|
| First $1,000 | 0% (Included with Gold) |
| $1,000 to $50,000 | 5.25% |
| $50,000 to $100,000 | 5.05% |
| $100,000 to $1,000,000 | 4.75% |
| $1,000,000+ | 4.50% |
- First $1,000 is interest-free: You can borrow up to $1,000 at 0% interest, covered entirely by your $5 monthly Gold subscription.
- Tiered rates on balances over $1,000: For loans up to $50,000, you pay 5.25% on the balance exceeding $1,000. Your rate drops to 5.05% on balances between $50,000 and $100,000, and reaches 4.75% on balances above $100,000.
- Simple cash withdrawals: With Robinhood's "Margin Spending" enabled, you can transfer borrowed cash straight to your outside bank account via ACH, or spend it directly using your Robinhood debit card.
3. Traditional Brokers: How to Negotiate an SBLOC (Fidelity, E*TRADE, Schwab)
If your investments are already sitting at big name brokerages like Fidelity, E*TRADE, or Charles Schwab, whatever you do, don't borrow at their published retail margin rates. Those rates are only for people who don't know any better.
Instead, if you have decent assets with them (usually $500,000 or more across your accounts), you can negotiate directly through their private client or banking desks:
Fidelity Investments (PCG & SBLOC)
Fidelity's posted margin rates ↗ are over 11%. But if your household accounts exceed $500,000, call the Private Client Group Margin Desk. They routinely discount margin rates down to SOFR + 1.0% to 1.5% (around 4.88% to 5.38%). For larger balances, they can also set up a custom SBLOC line through their partnership with Goldman Sachs. (See our guide on automating investments with Fidelity).
Spending: Transfer directly into a Fidelity Cash Management account (with free checkwriting, bill pay, and ATM fee reimbursements) or wire it out directly.
E*TRADE / Morgan Stanley Private Bank
E*TRADE offers a dedicated Line of Credit through Morgan Stanley Private Bank. Review standard terms on E*TRADE Margin & Lines of Credit ↗. Because it's set up as a separate credit facility pledged against your taxable account, it doesn't interfere with your daily trading margin. (Learn more in our E*TRADE automated investing guide).
Spending: Comes with a dedicated checkbook, wire access, and a personal loan rep.
Charles Schwab Pledged Asset Line (PAL)
Schwab Bank offers the Charles Schwab Pledged Asset Line (PAL) ↗, a dedicated line of credit collateralized by your Schwab taxable portfolio. Rates are pegged to SOFR plus a tiered spread based on how much you pledge.
One big perk: Unlike IBKR’s automated algorithm, if the market drops, a real person at Schwab will contact you first, giving you several business days to deposit cash or add collateral before any shares are sold.
4. The Fixed-Rate Alternative: SPX Box Spreads
What if you don't want to deal with floating interest rates at all, and you’d rather lock in a fixed interest rate for 1 to 3 years without talking to a single loan officer?
That’s where a box spread comes in. It sounds intimidating, but the core concept is surprisingly straightforward.
What is a Box Spread?
A box spread combines a bull call spread and a bear put spread using the exact same strike prices and expiration date:
- • Buy Call at Strike A + Sell Call at Strike B
- • Sell Put at Strike A + Buy Put at Strike B
Because the calls and puts cancel each other out completely, there is zero market direction risk. The payoff at expiration is 100% mathematically fixed at the difference between the two strike prices multiplied by $100.
How You Actually Borrow Cash with a Box Spread
- Sell the box spread for an upfront cash credit: You sell the box spread in your margin account, which immediately credits your account with cash today (for example, $190,000).
- Pay it off at expiration: When the options expire (say, 2 years later), the box settles for the fixed strike difference (for example, $200,000).
- The interest you pay: The $10,000 difference is your borrowing cost. Because market makers trade box spreads right alongside US Treasury bills, the implied interest rate is usually just 0.20% to 0.40% over Treasuries (currently around 4.1% to 4.4% fixed).
- Withdrawing the cash: That upfront cash credit sits in your brokerage cash balance. In a margin account, you can transfer that cash straight to your bank account via ACH or wire to buy real estate, fund a project, or cover an expense.
Do not ever try this with individual company stocks (like Apple or Tesla) or American-style ETFs (like SPY or QQQ).
The risk of early assignment: American-style options can be exercised early at any time by the person on the other side of the trade. If just one leg gets exercised early, your box structure breaks apart, leaving you with unexpected short shares and a massive margin call.
✅ You must ONLY trade box spreads on European-style, cash-settled index options such as S&P 500 Index Options (SPX) ↗ or Mini-SPX (XSP). European options cannot be exercised early under any circumstances, settle purely in cash at expiration, and receive favorable IRS Section 1256 ↗ tax treatment (60% long-term / 40% short-term capital gains).
Best Broker for Box Spreads: IBKR Pro
While several brokerages technically allow you to trade multi-leg options, Interactive Brokers (IBKR Pro) is widely considered the gold standard for executing SPX box spreads cleanly, affordably, and safely.
IBKR's Strategy Builder includes a built-in Box Spread template. You select SPX, choose your strikes and maturity, and submit all four legs together as one single order ticket with a net credit limit price. Zero risk of legging into individual legs.
IBKR's Portfolio Margin engine accurately calculates that European cash-settled box spreads have zero market directional risk. Your account collateral requirement equals only the net spread width, leaving your remaining portfolio buying power untouched.
IBKR charges standard low options commissions (~$0.65 per contract) with direct smart-routing to CBOE market makers. You get tight mid-market fills without the punitive multi-leg fees common at retail firms.
How to End a Box Spread Early (And What to Expect)
A common question is: What happens if you borrow cash via a 2-year or 3-year box spread, but you want to pay off the debt early?
Because you are trading exchange-listed options rather than signing a bank contract, you can close your box spread whenever the market is open. Here is how the early exit works, along with the benefits and consequences to keep in mind.
To close a short box spread early, you simply execute the mirror image of your opening trade. You buy the box spread back as a single four-leg combo order (buying the bull call spread and selling the bear put spread at your original strikes and expiration) for a net debit. On IBKR Pro, you right-click your existing combo position, click Close Position, and enter a limit order near the mid-market price.
- Early debt clearance: If you sell a property, receive a bonus, or secure cheaper financing elsewhere, buying back the box eliminates the liability and frees up collateral instantly.
- Bond discount savings if rates rise: Box spreads are priced like zero-coupon bonds. If benchmark interest rates rise after you sell the box, the market discount rate increases, meaning the box becomes cheaper to buy back early. You can close your debt at a discount, capturing an effective profit or interest savings.
- Early payoff penalty if rates fall: If market interest rates decrease after you sell the box, buying it back early will cost more than the linear amortized payoff. You effectively pay a premium to exit early because prevailing yields dropped.
- Four-leg bid-ask friction: Exiting requires trading four separate option contracts simultaneously. Crossing the bid-ask spread on all four legs can cost between $0.50 and $2.00 per spread in execution slippage.
- Section 1256 tax timing: SPX options are IRS Section 1256 contracts (taxed at 60% long-term / 40% short-term capital rates). Closing early realizes that gain or loss in the current tax year rather than letting it settle at scheduled expiration.
How Borrowing Rates Change Over Time (And What to Do About It)
Every floating-rate tool in this guide (Interactive Brokers margin, Robinhood Gold, Schwab PAL, and Fidelity SBLOCs) is anchored directly to the Secured Overnight Financing Rate (SOFR), which moves in lockstep with the Federal Reserve's target interest rate.
When the Fed alters monetary policy, your borrowing costs shift almost immediately. When benchmark rates climbed from near-zero to over 5.0% in 2022 and 2023, variable margin rates surged from roughly 1.5% to more than 6.5%. Conversely, when the Fed cuts rates, floating margin costs decline automatically without any refinancing paperwork, appraisals, or closing fees. Box spreads, on the other hand, fix your borrowing cost on the day you trade, immunizing you from rate changes until expiration.
Macro Rate Playbook: 4 Actions to Take
Never borrow based only on what interest rates look like today. Run your numbers assuming borrowing costs jump by 200 to 300 basis points. Confirm that your rental income, salary, or portfolio cash flow can comfortably cover higher interest expenses without forcing asset sales.
When interest rates are historically low or expected to rise, sell 1-year to 3-year SPX box spreads to lock in cheap fixed financing. When interest rates are peak or projected to drop, stay in floating margin or SBLOCs so your borrowing expense naturally drifts downward over time.
Your broker's spread over SOFR is not permanent. Whenever your taxable assets pass major milestones ($500,000 or $1,000,000), call your brokerage margin desk or wealth advisor. Shaving just 0.50% off a $300,000 balance saves $1,500 every single year in cash interest.
Unpaid margin interest compounds automatically into your outstanding principal. Enable monthly cash transfers or route your quarterly dividend payouts directly toward interest paydowns so rising rates do not cause your loan balance to balloon unattended.
Which Option Makes the Most Sense for You?
Winner: Robinhood Gold. Traditional brokers charge 11%+ at this tier. Robinhood gives you 0% on your first $1,000, and tiered rates from 5.05% to 5.25% on balances up to $100,000, with easy transfers to your bank or debit card.
Explore Recommended Brokerages →Winner: Interactive Brokers (IBKR Pro). Unbeatable automated rates (SOFR + 0.50% to 1.0% for balances over $100,000, putting rates at ~4.38% to 4.88%), zero phone negotiations, and straightforward wires. Just remember to keep your borrowing conservative (under 20% LTV) because of their automatic liquidation engine.
View IBKR Pro & Tools →Winner: Fidelity or Morgan Stanley / E*TRADE SBLOC. Negotiate your spread down to SOFR + 1.0% to 1.25% (around 4.88% to 5.13%). You get a separate credit line with checks, wires, and human customer service that gives you a grace period if the market pulls back.
Review Part 1 SBLOC Playbook →Winner: SPX Box Spreads (on IBKR or Fidelity). If you want certainty, this lets you lock in fixed borrowing costs near the Treasury curve (4.1% to 4.4%), and you can wire the upfront credit directly to your bank.
Analyze Real Estate Cash Flows →A Few Ground Rules Before Borrowing
No matter which route you take (IBKR Pro, Robinhood Gold, a private bank SBLOC, or a European box spread), here are three rules I always stick to:
- Keep total debt under 20% to 25% LTV: Never let your total loan balance exceed 25% of your diversified stock portfolio. Under FINRA Rule 4210 ↗, standard margin maintenance is set at 25% to 30%. If you borrow 25% against broad index funds like VOO ↗ or VTI ↗, the market would need to crash by over 65% before you'd ever face a margin call.
- Have a clear payoff plan: Always know in advance how you plan to pay off the balance, whether that’s from rental property cash flow, regular W-2 savings, an upcoming bonus, or refinancing into a traditional mortgage once rates drop.
- Know the tax deduction rules: In many situations, interest on money borrowed against your taxable portfolio can be tax-deductible (under IRS Section 163(d) for investment interest using IRS Form 4952 ↗, or on Schedule E if you used the cash for rental real estate). Be sure to check with your CPA on tracing rules.
Review the tax shielding mechanics, LTV crash formulas, and SBLOC negotiation scripts in Part 1, then check out our free calculators to model your loan numbers.
For more frameworks on building passive income, managing leverage, and designing your path to financial freedom, check out The Principles of Financial Independence (FIRE).
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Trending & Popular Guides
How to Set Up a Mega Backdoor Roth With Fidelity
How to Set Up a Backdoor Roth IRA With Fidelity
How to Set Up Automatic Investing with Fidelity
How to Set Up Automatic Investing with E*TRADE
Related Articles & Guides
View all guides
How to Borrow Against Your Stocks at Lower Rates Than a Mortgage (Part 1: SBLOC vs. Margin Guide)
How high earners and high-net-worth investors borrow against taxable stock portfolios at interest rates lower than mortgages. Part 1 covers SBLOC vs. margin mechanics, avoiding capital gains taxes, and calculating safe LTV to eliminate margin calls.
Should You Turn On DRIP? The Pros, Cons, and Tax Traps for High Earners
Dividend reinvestment plans (DRIP) offer frictionless compounding, but they can trigger unexpected tax complications in taxable accounts. Here is when to turn DRIP on—and when to keep your cash.
Bad Debt, Better Debt
Okay, you made a mistake of carrying your credit card balance over one month. So what? It’s just a month. Next, you continued to carry that balance over one more month. No problem,
Discussion 0
Questions, thoughts, or experience to share on Best Firms to Borrow Against Stocks: Lowest Margin Rates, IBKR Pro, Robinhood Gold & Box Spreads (Part 2)? Join the conversation below.