
Bad Debt, Better Debt
Listen to Full Article
ReadyFull article audio (6 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: Bad Debt, Better Debt
Okay, you made a mistake of carrying your credit card balance over one month. So what? It’s just a month. Next, you continued to carry that balance over one more month. No problem, you’ll pay it off in the 3rd month for sure. Uh oh, time has really gotten away, and now it’s been an entire year, and that balance has really grown! Now you’re in a real pickle and don’t know how to stop the vicious cycle. To make matters worse, you don’t have enough cash in the bank to pay down that high interest debt! If that sounds like you, you’ll likely be interested in debt consolidation -- a process, simply put, of getting a different loan with a much lower interest rate to pay off your high interest debt.
I like to call high interest debt, “bad debt,” and low interest rate debt, “better debt.” In this post, I won’t go into all the various ways of consolidating debt; instead I’ll only talk about using your primary home.
First, I’ll use an example to describe why that credit card balance is bad and how it grew over time. Let’s suppose that you started off with a $10,000 credit card balance with a 16% APR (annual percentage rate) and that you’ve carried that balance for an entire year. That balance accrued interest daily for the entire year, growing to a grand total of $11,761 -- a 17.6% increase over the initial amount. Ouch! And that’s assuming you’re not swiping that credit card for even more purchases.
One way to consolidate that debt would be to do a cash-out refinance mortgage on your primary home. Let’s use an example to describe how a cash-out refi works:
Your primary home: Estimated market value of $500K
Your current mortgage balance: $250K
With those numbers, that would mean you have $250K in equity. That is, your home’s market value minus your current mortgage balance. The equity is also the amount of your home you actually own. This amount is what we’ll tap into to consolidate that high interest debt we talked about earlier. In other words, a cash-out refi will allow you to withdraw money from the part of the home you already own and put it in your pocket (to pay off your high interest debt, that is). In addition, fixed mortgage rates are at the lowest levels in history. So that’s how we’re going to use “better debt” (3% interest rate give or take) to replace that sky high 16% APR on your credit card balance!
At the end of the cash-out refi process, this is what our balances look like*:
Your primary home: Estimated market value of $500K
Your new mortgage balance: $250K + $11,761 = $261,761
Your credit card balance: $0 (because you used the $11,761 from the cash-out refi and paid off that “bad debt”)
*For simplicity’s sake, I didn’t include fees incurred that the various parties involved in the refi process would charge you. But you absolutely need to pay attention to those fees when you shop around for a lender to work with.
In order to do a cash-out refi, most lenders will require you to have more than 20% of equity in your home. In our example, we have 50%, so we’d be in a solid position to qualify.
It’s very important to do your due diligence and shop around for a good interest rate offered by various banks & credit unions. Big banks may not always have the best rates, so search the internet for lenders in your area and ask for their current refi rates (Yelp can be a great starting point).
Lastly, I want to highlight that you can consolidate other types of debt, like student loans or medical bills, too. If you have multiple high-interest debts, I suggest paying off the ones with the highest interest rates first (likely credit cards) using the Debt Avalanche MethodA debt payoff strategy where you pay minimums on all obligations and throw all extra cash at the debt with the highest interest rate first, minimizing the total interest you pay..
Yes, cash-out refis will increase your current mortgage balance, but the amount you increase your balance is given to you as cash by the bank. It’s crucial that you only use that cash to pay off your high interest debt and nothing else, so you can finally put an end to the vicious cycle of carrying over that “bad debt!” Congratulations, now you know one solid way to use “better debt” to get rid of that “bad debt.”
💡 What If You Have a Stock Portfolio Instead of Home Equity?
If you don't own a home or don't want to pay $10,000+ in mortgage Closing CostsThe bundle of lender fees, appraisal costs, title insurance, and prepaid taxes paid out of pocket to originate an entirely new replacement loan., you can borrow against your taxable stock portfolio at interest rates often lower than a mortgage without selling shares or triggering capital gains taxes.
Explore our 2-part guide: Part 1: SBLOC vs. Margin Guide and Part 2: Lowest Borrowing Rates & Firm Comparison.
To compare paying down debt with investing, try the Debt vs. Investing calculator or the free Automate Your Wealth course.
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Download the Debt Avalanche vs. Investing Decision Tree
A one-page decision tree for weighing debt payoff against investing, based on interest rates and tax considerations.
- ✓ Rate and tax-adjusted decision steps
- ✓ Avalanche versus snowball overview
- ✓ Printable one-page flowchart
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this quick reference handy when managing your investments!
Your Next Step & Related Guides
View all resources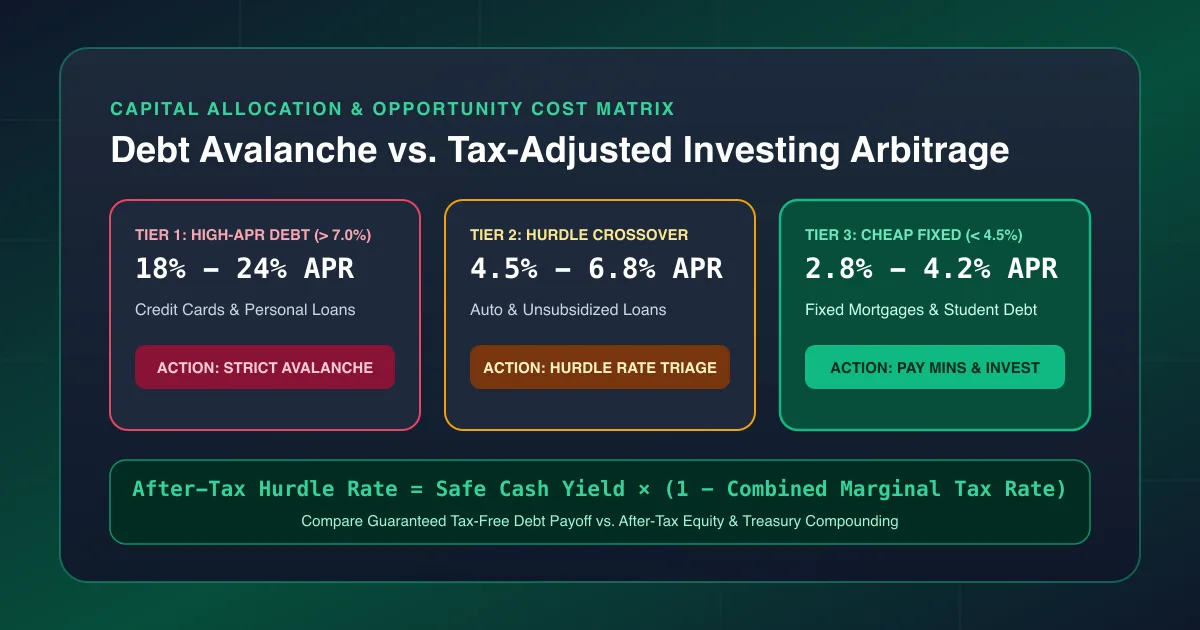
Debt vs. Investing Calculator
Model after-tax payoff versus investing over 3 to 10 years.
Pros and Cons of Retiring With Debt
When planning for retirement, one of the biggest hurdles you’ll face is deciding whether to retire with or without debt. Debt can be a strong wealth-building tool, but it carries r
With $8,200,000 In Debt, When Will I Be Debt Free?
In my previous post where I shared my $10 million FI/RE goal by age 40, I mentioned that my investment allocation will be 30% in real estate. That’s $3M of my own cash invested in r
Discussion 🟢 Open for Discussion 0