
How To Set Up a Backdoor Roth IRA With Fidelity
Listen to Full Article
ReadyFull article audio (7 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: How To Set Up a Backdoor Roth IRA With Fidelity
Download the Fidelity Backdoor Roth Execution Flowchart
A 1-page visual decision tree and Form 8606 compliance checklist to execute your conversion cleanly without pro-rata tax surprises.
- ✓ Visual 5-step conversion money flow
- ✓ Pro-rata rule exemption checklist
- ✓ Form 8606 line-by-line cheat sheet
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this checklist handy for retirement and tax planning!
Overview & The Pro-Rata Rule
In this step-by-step guide, I will walk through the steps to set up a Backdoor Roth IRA with Fidelity. If you don’t know the benefits of a Roth IRA, check out my post on Roth IRA vs 401(k) first. After reading it, you’ll know that performing a Backdoor IRA conversion is only useful if your 2026 income is above $153K (single) or $242K (married filing jointly).
Before proceeding, I advise you to consult a professional tax/financial advisor, as there may be hidden consequences to performing a Backdoor IRA.
For example, review the pro-rata rule A tax rule where the government looks at all your combined Traditional, SEP, and SIMPLE IRAs together. If you have any pre-tax money across your IRAs, you cannot convert just your after-tax dollars to a Roth tax-free. and how all your IRAs are treated as one aggregate account, which may trigger some unintentional tax consequences. If you don’t have any tax-deferred money in any existing IRAs or if you don’t have any IRAs at all, setting up a Backdoor IRA should be relatively straightforward.
Exploring Roth Strategies?
Planning larger annual Roth contributions or looking ahead to early retirement distributions? Check out our Mega Backdoor Roth Calculator for 401(k) plans and our Roth Conversion Ladder Calculator to map penalty-free early retirement withdrawals.
Step-by-Step Backdoor Roth Conversion
There are several ways to set up a Backdoor IRA. But for the sake of simplicity, I will focus only on converting a Traditional IRA to a Roth IRA using cash (instead of assets).
Step 1: Open a Traditional IRA with Fidelity
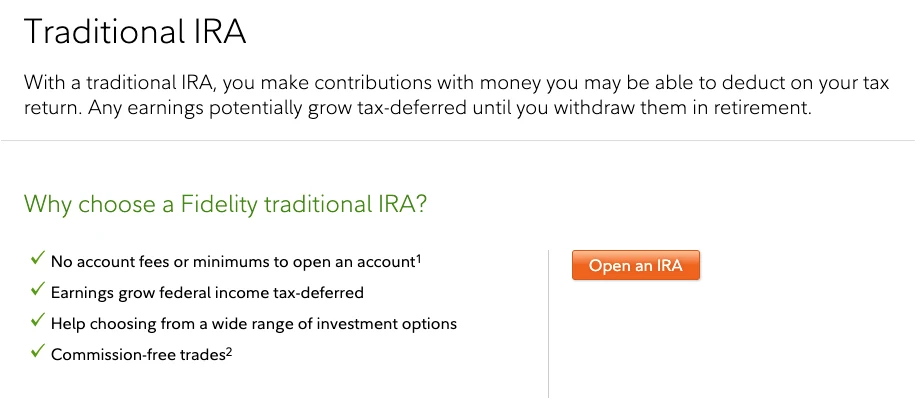
Go to Fidelity Traditional IRA and follow the step-by-step guide to open an account.
Step 2: Link Your Bank Account
Since this may be your first time using Fidelity, you will need to link a funding bank account before setting up a deposit.
a) Go to https://digital.fidelity.com/ftgw/digital/bank-setup .
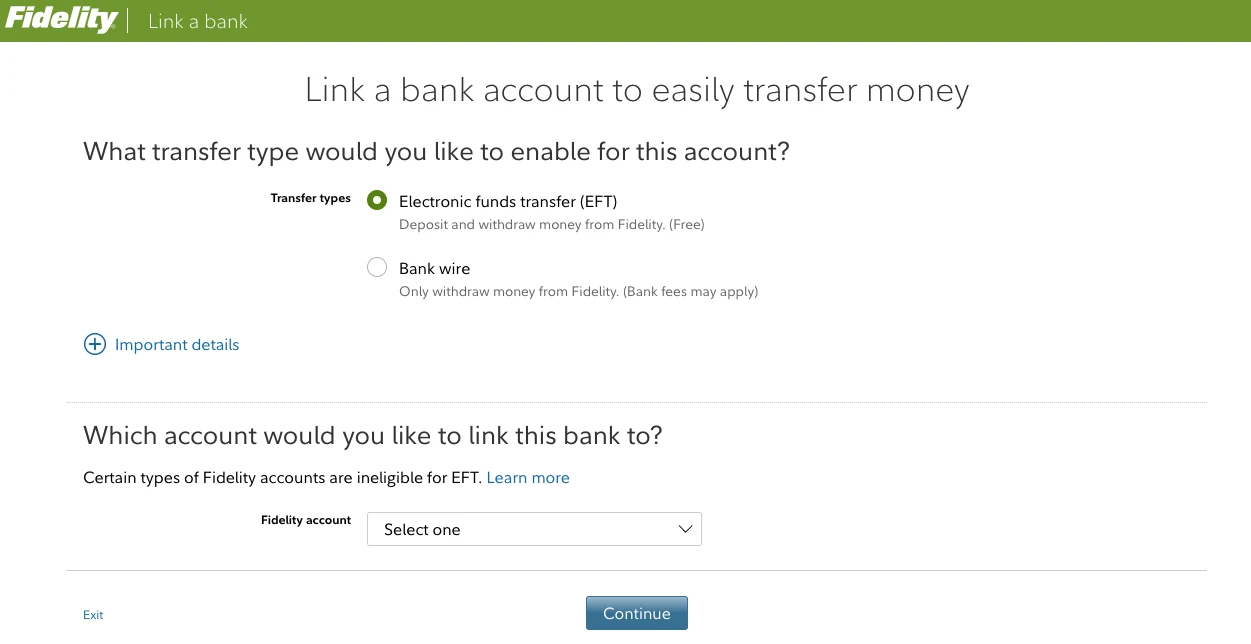
b) Select which transfer type you’d like to use. I usually use electronic funds transfer (EFT) since banks usually have $0 fees. However, there’s a 1-3 business day settlement period for your cash to settle in your Traditional IRA. Wire transfers are faster but banks may charge a fee.
c) Select your newly-created Traditional IRA account to link your bank account to.
d) Fill out the remaining fields as requested by Fidelity.
Step 3: Fund Your Traditional IRA (Non-Deductible)
After linking your bank account, transfer your non-deductible contribution into your Traditional IRA. After you finish linking a bank account to your Traditional IRA, now it's time to make your first contribution.
a) Go to https://digital.fidelity.com/ftgw/digital/transfer/ .
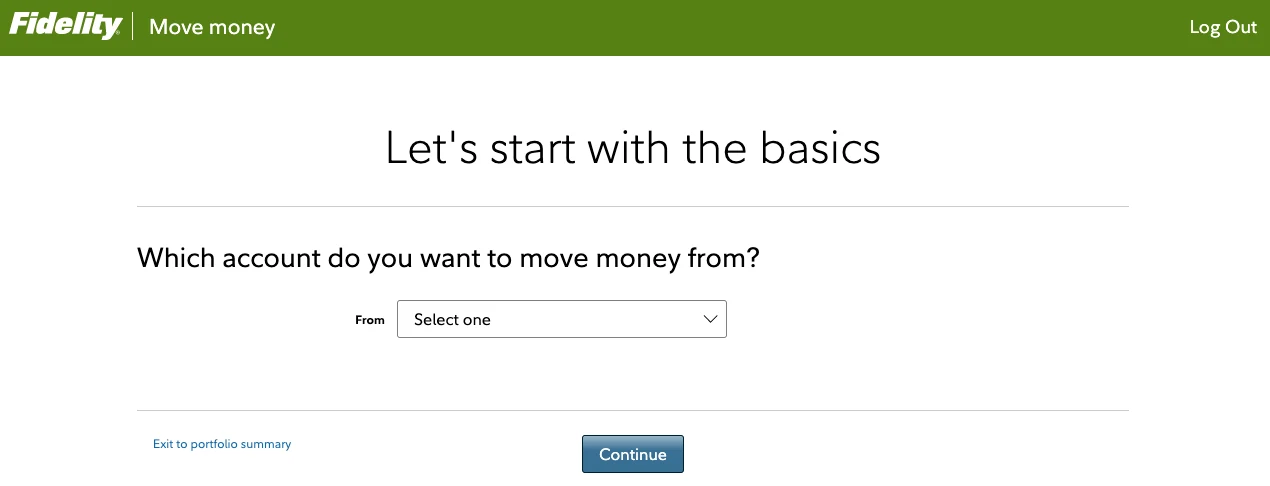
b) Select which account to move money from. If you just linked a new bank account in Step 2, you’ll likely want to select that bank account. If you’re an existing Fidelity customer, it’s also possible to select another investment account like an individual Fidelity brokerage account that contains cash.
Send this to your inbox (includes the free newsletter)
✉ No spam. Unsubscribe anytime with 1 click.
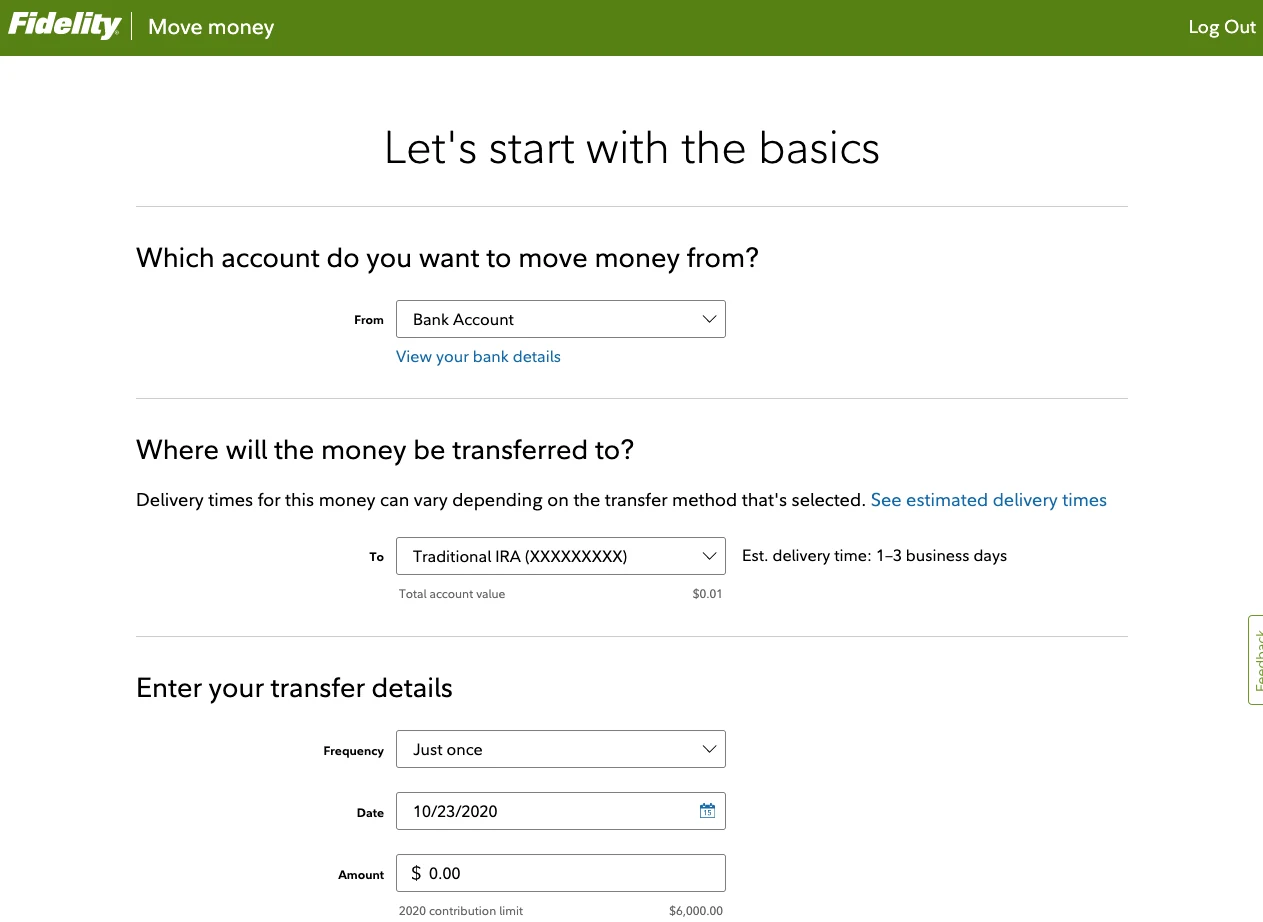
c) Next, select your Traditional IRA as the account the money should be transferred to. As I mentioned previously, you’ll notice that the estimated delivery time of the cash deposit is 1-3 business days.
d) For “Frequency,” select “ Just once.”
e) Enter a “Date” you wish to transfer money from your bank into your account.
f) For “Amount,” you may contribute up to $7,500. If you’re 50 or older, you can contribute up to $8,600.
Note
Step 4: Wait for Cash Settlement (3–5 Business Days)
Wait 3-5 business days for your funds to settle. Personally, I prefer a “clean” conversion from a Traditional IRA to a Roth IRA. So every year that I perform a Backdoor IRA conversion, I wait for my funds in my Traditional IRA and do not invest a single dollar. I only invest after the Backdoor IRA conversion.
Step 5: Open a Roth IRA with Fidelity
Similar to Step 1, open a Roth IRA account. Don’t fund it directly, because we are doing a Backdoor IRA conversion, so the funds will come from your Traditional IRA in the next step.
a) Go to Fidelity Roth IRA and follow their step-by-step guide.
Step 6: Execute the Backdoor Roth Conversion
To complete the conversion, transfer the settled cash from your Traditional IRA directly into your Roth IRA. Since settlement times vary, attempt this step after your deposit clears:
a) Go to Fidelity Transfers .
b) Select your Traditional IRA under "Transfer From".
c) Select your Roth IRA under "Transfer To" and complete the conversion.
Step 7: Invest Funds & File IRS Form 8606
Congratulations! That’s it. You’ve successfully set up a Backdoor Roth IRA. Remember to invest the cash inside your Roth IRA and file IRS Form 8606 at tax time.
If you’re interested in learning about another way to grow even more of your investments tax-free, read my blog post on the Mega Backdoor Roth (or check our 401(k) Benefits by Company directory to verify if your employer allows after-tax contributions) or how to set up automatic investing .
- Do Not Invest Before Converting: Leave your Traditional IRA deposit in uninvested core cash (
SPAXX) while waiting 1 to 3 business days for EFT settlement. Only buy ETFs or mutual funds after the cash lands inside your Roth IRA. - Residual SPAXX Pennies: If $1 to $5 of interest posts to your Traditional IRA at month-end, simply run a second 30-second conversion of those pennies into your Roth IRA.
- Fidelity Mobile App Shortcut: Tap Transact → Transfer → From: Traditional IRA → To: Roth IRA and select Keep Traditional IRA Open so the account stays ready for next year.
Disclaimers
- All screenshots were taken in 2020 from Fidelity.com and may be subject to change.
- Backdoor IRA conversions are sanctioned by the IRS as of 2026, but rules may change in the future.
- Roth IRA income and contribution limits may differ in future years.
- This is not advice. Reach out to a tax/financial advisor for professional assistance.
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Frequently Asked Questions
Quick answers to common questions, technical edge cases, and tax rules.
How do I avoid the IRS pro-rata rule when doing a Backdoor Roth?
The IRS aggregates all your Traditional, SEP, and SIMPLE IRAs as of December 31 of the conversion year. To avoid paying taxes on pre-tax money, you must have a $0 total pre-tax IRA balance by year-end. You can achieve this by rolling any existing pre-tax IRA balances into your current employer 401(k), which is excluded from the pro-rata calculation.
Do I have to wait between depositing to Traditional IRA and converting to Roth?
You only need to wait until the deposit fully settles into cash (typically 1 to 3 business days at Fidelity). Once the cash shows as "Available to Withdraw / Convert", execute the conversion immediately to minimize taxable interest earnings while the cash waits in the core sweep fund.
How is a Backdoor Roth IRA reported on my annual tax return?
You must file IRS Form 8606 with your Form 1040. Part I records your non-deductible basis (showing you already paid income tax on the contribution), and Part II reports the conversion into the Roth IRA, resulting in zero net taxable income on the original principal.
Can I do a Backdoor Roth if I already have a SEP-IRA or SIMPLE IRA?
Yes, but any pre-tax balances in SEP or SIMPLE IRAs will trigger the pro-rata rule unless they are rolled into an active 401(k) before December 31 of the conversion year. If that rollover is not possible, a pro-rated percentage of your conversion will be taxable.
When performing a Backdoor Roth IRA with Fidelity, do I need to invest the cash into securities before converting?
No. Do NOT invest the cash into stocks, ETFs, or mutual funds while it is inside your Traditional IRA. Leave the deposit in your core cash position (SPAXX) until it settles, execute the Roth conversion of the cash into your Roth IRA, and then purchase your index funds or ETFs inside the Roth IRA so all future growth is 100% tax-free.
Can I complete a Fidelity Backdoor Roth IRA conversion on the Fidelity mobile app?
Yes. In the Fidelity mobile app, tap "Transact" at the bottom navigation bar, select "Transfer", choose your Traditional IRA as the "From" account and your Roth IRA as the "To" account, select "Full Account" or "Partial" transfer, and choose to keep your Traditional IRA open for next year’s contribution.
Your Next Step & Related Guides
View all resources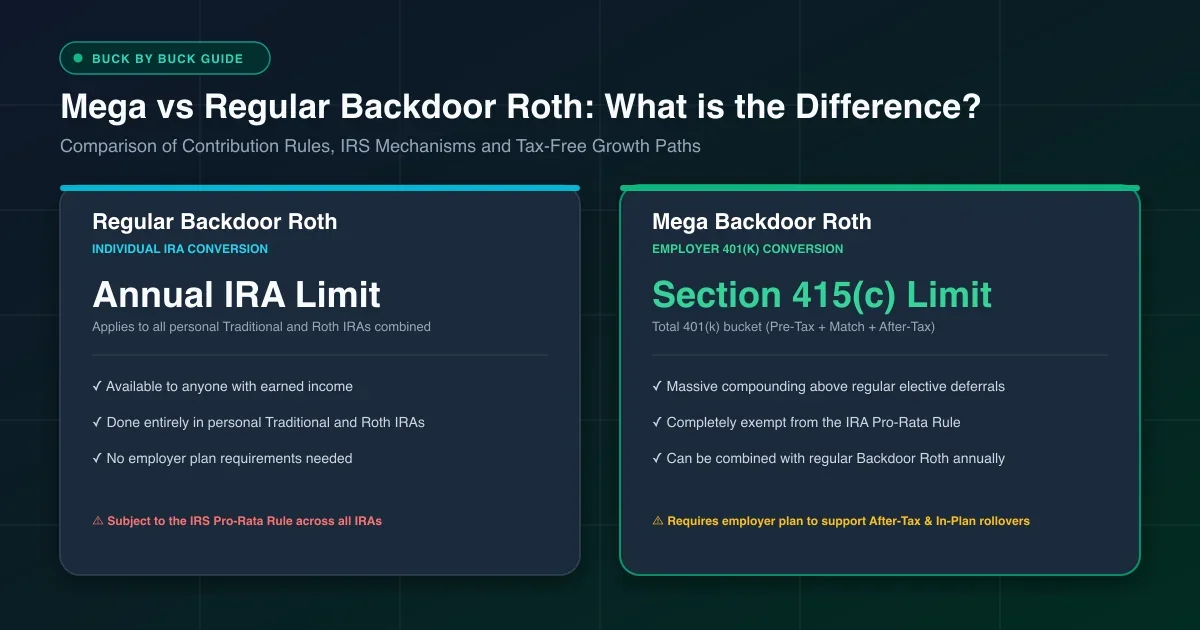
Mega Backdoor Roth Calculator
Estimate your remaining after-tax 401(k) contribution space.
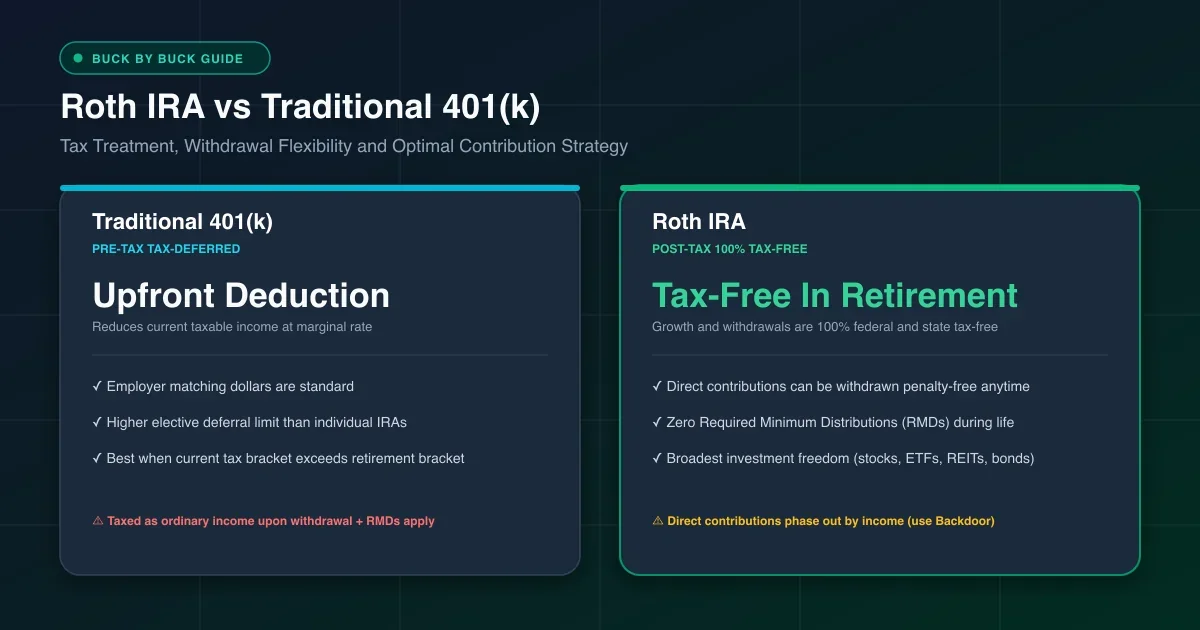
Roth IRA or 401(k): Which One Is Right For You?
I hear it all the time, “Should I invest in a Roth IRA or a 401(k)?” To help you answer that question, first we need to know what they are and what some of their benefits are. From
6 Reasons Why I Invest In Stocks to Build Wealth
A few months ago, I wrote an article on why I invest in real estate to build wealth. While I am a huge fan of real estate investing, there are many benefits of investing in stocks
Discussion 🟢 Open for Discussion 0