
How To Set Up a Mega Backdoor Roth With Fidelity
Listen to Full Article
ReadyFull article audio (7 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: How To Set Up a Mega Backdoor Roth With Fidelity
Download the Mega Backdoor Roth Decision Tree & Math Matrix
A 1-page visual guide to Section 415(c) after-tax space calculations, compensation ceilings, and automated daily in-plan conversion protocols.
- ✓ Section 415(c) headroom formula
- ✓ 4-point employer plan eligibility gate
- ✓ Fidelity daily automated conversion steps
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this checklist handy for retirement and tax planning!
In this step-by-step guide, I will walk through the steps to set up a Mega Backdoor Roth with Fidelity. Specifically, I will outline the steps to set up an Mega Backdoor Roth using an “in-plan conversion” (as opposed to the tedious and tax-ineffective “ in-service conversion”).
Additionally, if you don’t know the differences between the regular Backdoor Roth and the Mega Backdoor Roth conversions, read my blog post first!
Prerequisites: Employer 401(k) Plan Rules
-
Your employer’s 401(k) plan needs to allow after-tax contributions. Without this option, you can’t do a mega backdoor Roth. You can check our List of 401(k) Benefits by Company to see if your employer supports after-tax contributions, or verify with your employer’s HR team.
-
Your employer’s 401(k) plan allows for “in-plan” rollovers to a Roth 401(k) or “in-service” withdrawals to a Roth IRA.
If neither is offered, you can’t touch your after-tax contributions in your 401(k). Therefore, your earnings would grow tax-deferred, not tax-free! In that case, I’d recommend avoiding the Mega Backdoor Roth altogether. It’s actually worse to invest after-tax dollars in a traditional 401(k) than a regular brokerage account because 401(k) withdrawals are taxed as ordinary income, not (long-term) capital gains!
Prerequisite #2: While there are 2 ways to set up a Mega Backdoor Roth , I will focus only on using the “in-plan conversion” method, which is the fully-automated approach and doesn’t come with the tax headaches that the “in-service conversion” method does.
Interactive Tool: Calculate Your Max Contribution
Planning your payroll deductions? Use our free 2026 Mega Backdoor Roth Calculator to determine your exact remaining after-tax space, employer match cap, and per-paycheck contribution schedule.
Step-by-Step Mega Backdoor Setup
Step 1: Login to Fidelity NetBenefits 401(k)
Click here and login using your Fidelity.com credentials. You should land on a page that asks you to select which account you want to modify. Select your company’s 401(k) plan from the dropdown.
Step 2: Adjust After-Tax Contribution Percentage
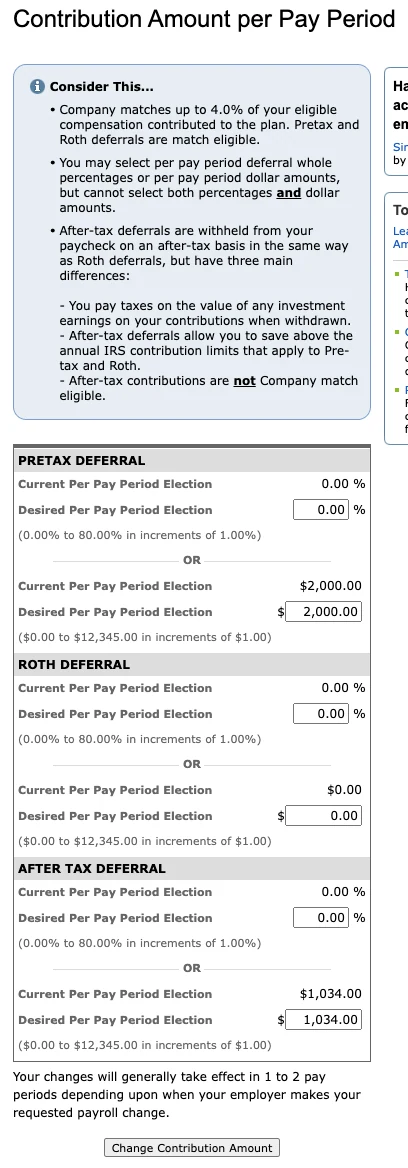
a) You’ll be taken to a page with a section that says, “Manage Your Contribution Amount.” Click the link called “Contribution Amount.” You’ll find yourself on a page that allows you to change your “Contribution Amount per Pay Period”:
Send this to your inbox (includes the free newsletter)
✉ No spam. Unsubscribe anytime with 1 click.
Note
b) Here’s where the magic happens.
The Pretax Deferral section is for your normal pre-tax traditional 401(k). The max contribution limit here is $24,000 in 2026.
The Roth Deferral section is for normal post-tax Roth 401(k) deferrals. I don’t contribute anything here because I prefer maxing out my pre-tax traditional 401(k) to lower my taxable income today.
The After Tax Deferral section is where you set up your post-tax Mega Backdoor Roth contributions!
How much you can contribute is calculated using the following formula:
-
In 2025: Max Mega Backdoor Roth contributions = $70,000 - (employee 401(k) contributions) - (employer match contributions)
-
In 2026: Max Mega Backdoor Roth contributions = $71,000 - (employee 401(k) contributions) - (employer match contributions)
For example, in 2026, if you max out your traditional 401(k) at $24,000 and your employer match contributions are $15,000, then your max Mega Backdoor Roth contributions would be $32,000. That is, $71,000 - $24,000 - $15,000 = $32,000.
Step 3: Call Fidelity to Enable Automatic In-Plan Conversions
This step is simple. Just call Fidelity Workplace Planning at 800-557-1900, and tell them you’d like to add “Automatic Roth In-Plan Conversion” to your account. If the person who answers happens to not know how to do that, just call them again later.
Warning
Step 4: Verify Your Mega Backdoor Conversion Setup
a) After you receive your next paycheck, log back into fidelity.com .
b) Click on your 401(k) account.
c) In the main area of the page, you will see an “I Want to…” section. Click on “View Balances.”
d) You should see a pie chart called “Sources.” For example:
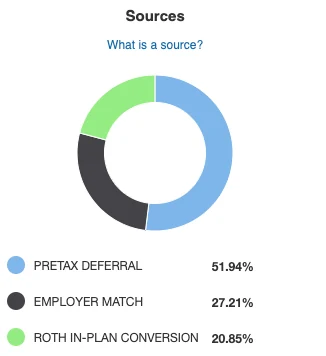
If you see “Roth In-Plan Conversion” in the legend, you’re all set! If not, be sure to double check all previous steps. Call Fidelity if you’re still having trouble.
Step 5: Confirmation & Next Steps
That’s it. You’ve successfully set up a Mega Backdoor Roth ! Now you can start watch your post-tax contributions grow tax-free!
If you’re interested in learning about another way to grow even more of your investments tax-free, read my other step-by-step guide to do a regular Backdoor Roth ! I’ve also created a guide on how to setup automatic investing , as well.
- Online Button vs. Calling Fidelity: Some employer plans display a self-serve "Convert to Roth" toggle directly inside NetBenefits under Contributions → Automatic Roth Conversions. If your plan only allows manual conversions online, call Fidelity Workplace Services at 800-835-5095 and say: "Please enable automated daily in-plan Roth conversions for my future after-tax 401(k) contributions."
- Fidelity Solo 401(k) Limitation: Fidelity's standard prototype Self-Employed 401(k) does not support voluntary after-tax contributions. Self-employed owners need a custom non-prototype Solo 401(k) plan document to run a Mega Backdoor Roth at Fidelity.
- Check Employer Eligibility: Verify your company's exact match and Mega Backdoor support in our Employer 401(k) Benefits Directory.
Disclaimers
- All screenshots were taken in 2021 from Fidelity.com and may be subject to change.
- Mega Backdoor Roth conversions are sanctioned by the IRS as of 2026, but rules may change in the future.
- 401(k) contribution limits may differ in future years.
- This is not advice. Reach out to a tax/financial advisor for professional assistance.
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Frequently Asked Questions
Quick answers to common questions, technical edge cases, and tax rules.
Can I do a Mega Backdoor Roth if my employer does not use Fidelity?
Yes, as long as your employer 401(k) plan allows after-tax contributions (distinct from Roth 401(k)) and permits in-service withdrawals or in-plan Roth rollovers. While the user interface and phone numbers differ by plan custodian (like Vanguard or Empower), the core IRS rules under Section 415(c) remain identical.
How do after-tax 401(k) contributions differ from regular Roth 401(k) contributions?
Roth 401(k) contributions share the standard employee elective deferral limit ($24,000 in 2026). After-tax contributions, by contrast, sit in a separate non-elective bucket that can be funded up to the overall Section 415(c) plan limit ($71,000), after accounting for employee deferrals and employer match dollars.
What happens if investment earnings accrue before the conversion completes?
If earnings accumulate in the after-tax bucket before conversion, the gains are treated as taxable ordinary income upon conversion. Calling Fidelity to activate automated daily in-plan conversion ensures after-tax contributions convert immediately upon payroll settlement, preventing taxable earnings from compounding.
Do employer match contributions reduce how much after-tax money I can put in?
Yes. The IRS Section 415(c) annual additions ceiling ($71,000 in 2026) encompasses employee elective deferrals, employer matching or profit-sharing contributions, and after-tax dollars combined. Use our Mega Backdoor Roth Calculator to calculate your exact headroom.
Where is the Fidelity Mega Backdoor Roth button in NetBenefits, or do I need to call?
In Fidelity NetBenefits, navigate to your 401(k) plan -> "Contributions" -> "Contribution Amount" to set your After-Tax percentage. For the conversion itself, check "Rollovers" or "Change Investments" -> "Convert to Roth" for an online toggle ("Convert My After-Tax Contributions"). If your employer plan does not display the online automatic toggle, call Fidelity Workplace Investing at 800-835-5095 and ask the representative to enable "Automated Daily In-Plan Roth Conversions" on your after-tax bucket.
Does a Fidelity Solo 401(k) (Self-Employed 401k) allow a Mega Backdoor Roth?
No. Fidelity’s standard off-the-shelf prototype Self-Employed 401(k) only supports pre-tax (and newly added Roth elective) contributions and does not allow voluntary after-tax employee contributions or in-plan Mega Backdoor conversions. To execute a Solo 401(k) Mega Backdoor Roth while keeping assets custodialized at Fidelity, you must use a third-party custom non-prototype Solo 401(k) plan provider that explicitly includes after-tax and in-plan conversion provisions.
How do I check if my employer Fidelity 401(k) plan (such as McKinsey, Lam Research, Optum, or Cleveland Clinic) allows a Mega Backdoor Roth?
Log into NetBenefits and click "Contributions" -> "Contribution Amount". If you see a third input line labeled "After-Tax" (separate from Pre-Tax and Roth), your plan passes Prerequisite 1. Next, check your Summary Plan Description (SPD) under "Plan Information & Documents" for "In-Plan Roth Rollover" or "After-Tax In-Service Withdrawal", or check our Company 401(k) Mega Backdoor Directory.
Your Next Step & Related Guides
View all resources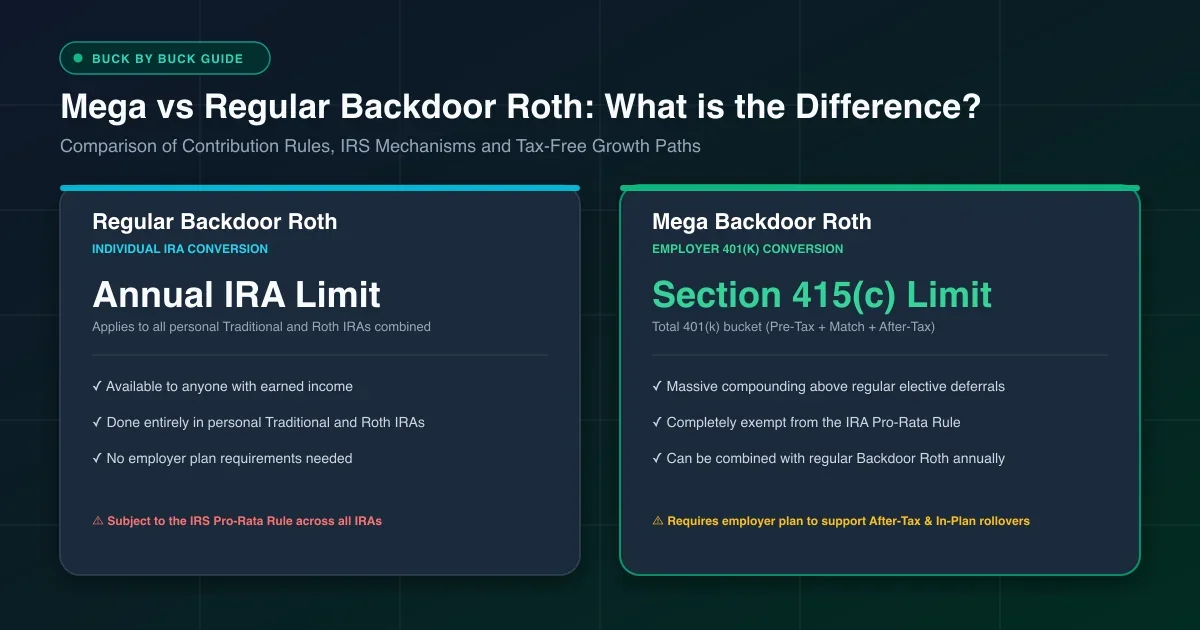
Mega Backdoor Roth Calculator
Estimate your remaining after-tax 401(k) contribution space.
Mega vs Regular Backdoor Roth: What's the Difference?
For high income earners, the Backdoor Roth conversion is a popular way to get around the income limits that prevent high earners from contributing directly to a Roth IRA. The Mega
What's A Mega Backdoor Roth?
If you like your Roth IRA for its tax-free growth, you’re really going to like a mega backdoor Roth! Contributions to a Roth IRA are funded with after-tax dollars and earnings grow
Discussion 🟢 Open for Discussion 0