
🪜 Early Retirement & Tax Strategy
Zero-Tax 5-Year Sequencing
Roth Conversion Ladder & Tax Bracket Optimizer
Bridge the gap to early retirement without the 10% IRS penalty. Model your annual conversion pipeline, project cumulative tax liabilities, and optimize your conversions against federal brackets and ACA subsidy thresholds.
⚙️ Retirement & Conversion Assumptions
Updated with projected IRS 2026 tax brackets & standard deductions.
Year 1 Conversion Impact
12% Marginal
Estimated Year 1 Tax Liability
$0
Effective Federal Tax Rate: 0.0%
Gross Income (MAGI):
$0
Taxable Income:
$0
Healthcare / ACA Subsidies
--% of Federal Poverty Line (FPL)
Your MAGI falls within optimal ACA premium tax credit ranges.
Cumulative Horizon Projection
5-Year Maturation Pipeline 5-Year Rule
Yr 1 Convert
Yrs 2-4 Aging
Yr 5 Clock Closes
Yr 6+ Unlocked 100% Penalty-Free
Each annual conversion matures after 5 full tax years, unlocking tax-free principal before age 59½.
Total Converted to Roth:
$0
Cumulative Taxes Paid:
$0
Penalty-Free Roth Available at Year 5:
$0
Was this calculation helpful?
📬
Email My Conversion Ladder Schedule (includes the free newsletter)
Did you mean ? Click to fix.
✉ No spam. Unsubscribe anytime with 1 click.
Year-by-Year Roth Conversion Schedule & 5-Year Unlock Timeline
Each conversion tranche becomes 100% penalty-free for withdrawal after 5 full calendar tax years.
| Year | Conversion ($) | MAGI ($) | Fed + State Tax ($) | Pre-Tax Remainder ($) | Tranche Unlocks |
|---|
How the 5-Year Roth Conversion Ladder Works in Early Retirement
IRS rules normally impose a 10% early withdrawal penalty on pre-tax retirement accounts (like Traditional 401(k)s and IRAs) taken before age 59½. The Roth Conversion Ladder is a premier tax strategy enabling early retirees to access their retirement nest egg completely penalty-free.
TL;DR Calculation Formulas: Roth Conversion Pipeline & 5-Year Seasoning
Taxable Conversion Tranche = Total Amount Converted from Pre-Tax 401(k)/IRA
Effective Tax on Tranche = Taxable Conversion Tranche × Marginal Tax Bracket Rate
Penalty-Free Unlock Date = January 1st of Tax Year (Conversion Year + 5)
Bridge Runway Required = Annual Living Expenses × 5 Years (Funded via Taxable/Cash)
1️⃣ Convert Annually
Roll a targeted dollar amount each year from your Traditional pre-tax account into a Roth IRA. You pay ordinary income taxes on the converted amount in that tax year.
2️⃣ Wait the 5-Year Clock
Each individual conversion tranche has its own 5-year seasoning period. During these first 5 years of early retirement, you live off taxable brokerage accounts, savings, or cash buffers.
3️⃣ Withdraw Penalty-Free
Beginning on January 1st of Year 6, the Year 1 conversion principal is unlocked and can be withdrawn with zero penalty and zero additional tax.
The Age 59½ Inflection Point & The Rule of 55
The 5-year seasoning requirement only applies to avoid the 10% early withdrawal penalty before age 59½ (IRC Section 72(t)).
🎯 Conversions Near Age 59½
Once you reach age 59½, all converted principal and earnings become penalty-free (assuming your Roth IRA has been open for 5 years). You do not need to wait 5 full years for conversions performed in your late 50s once you pass age 59½.
💼 The Rule of 55 Exception
If you leave your job in or after the calendar year you turn 55 (age 50 for public safety workers), you can take penalty-free distributions directly from that employer's 401(k) without needing a Roth conversion ladder.
📖 Want a deep dive into all early withdrawal strategies? Read our full breakdown: 3 Little-Known Ways To Access Your 401(k) Penalty-Free Before 59½ .
Tax Optimization & ACA Healthcare Subsidies
Because early retirees often have little to no earned income, you can convert funds through the lowest federal tax brackets (10% and 12%) and your standard deduction ($16,100 for Single, $32,200 for Married Filing Jointly in 2026).
ACA Premium Tax Credits: Conversions count towards your Modified Adjusted Gross Income (MAGI). Keeping your MAGI between 150% and 250% of the Federal Poverty Line (FPL) maximizes Silver plan Cost-Sharing Reductions (CSR) and minimizes health insurance premiums. Pair your conversion schedule with our When Can I Retire Simulator , the Zero-Tax Early Retirement Blueprint , and the Year-End Investment Checklist before executing your December 31 custodian transfer.
📥 Free Printable PDF Guide One-Page Reference • Instant PDF
Download the FI/RE Milestones & Safe Withdrawal Roadmap (PDF)
Printable reference chart detailing portfolio multiples from Coast FI to Fat FI, safe withdrawal rates by retirement horizon, and 5-year conversion ladder sequence.
- ✓ Clean, 1-page printable reference cheat sheet
- ✓ Instant direct access and email delivery
- ✓ Updated with current statutory limits & guidelines
✓
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this roadmap handy along your path to financial independence!
Mobile Handoff
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
🔖
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Your Next Step & Related Guides
View all resources
Interactive Game
Featured Tool
Can You Retire Early? (FIRE Game)
Test your tax and investing instincts across 8 career turns.
Play Game
Retirement • • ⏱ 19 min read
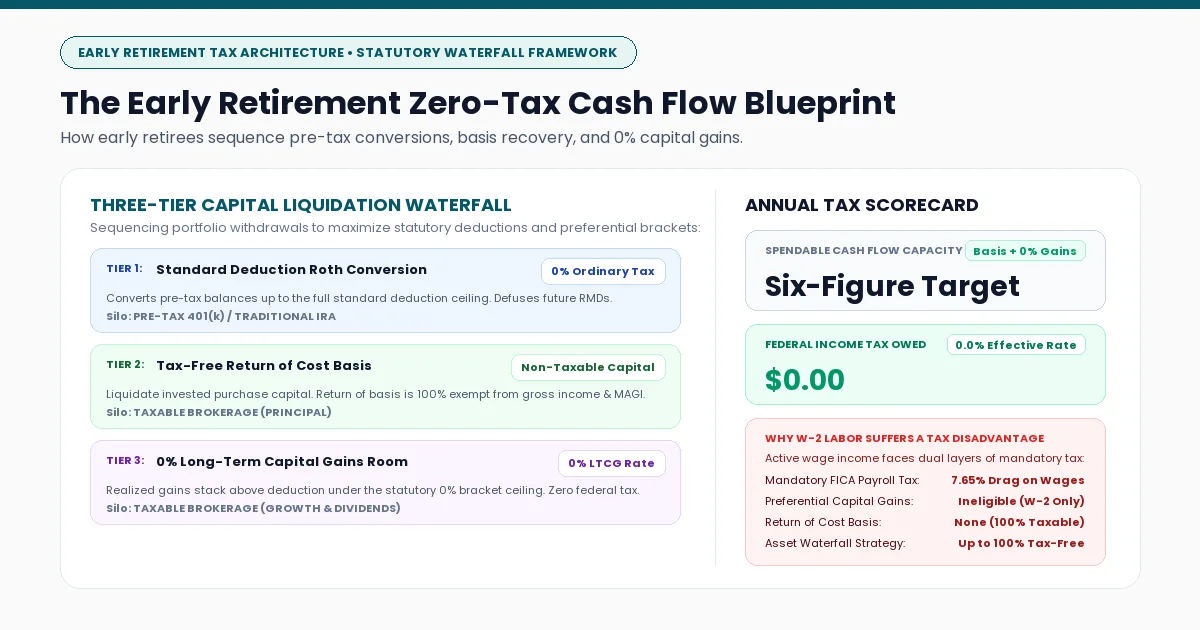
How Early Retirees Live on Six Figures Tax-Free with $0 in Federal Income Tax
Discover how early retirees engineer six-figure spendable cash flow while paying $0 in federal income tax using the strategic tax waterfall strategy.
Read guide
Stocks & Investing • • ⏱ 8 min read
Should You Turn On DRIP? The Pros, Cons, and Tax Traps for High Earners
Dividend reinvestment plans (DRIP) offer frictionless compounding, but can trigger tax traps in taxable accounts. Here is when to use DRIP and when to keep cash.
Read guide
Discussion 🟢 Open for Discussion 0