
6 Reasons Why I Invest In Real Estate to Build Wealth
Listen to Full Article
ReadyFull article audio (10 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: 6 Reasons Why I Invest In Real Estate to Build Wealth
I know plenty of successful investors who invest entirely in the stock market and in no other asset classes, like real estate. On the other hand, I also know many successful investors (myself included) who have done even better putting their money to work in real estate. Consider the following 6 reasons why I include real estate in my portfolio and why you should consider it too.
Diversification
If all your money is in one type of asset class, like stocks, then stock market crashes like the ‘08 crash or the most recent stock market crash of 2020 will probably make you panic and stress out! Think about if you were retired and relied strictly on stock dividends, only to suddenly see your nest egg plummet by 25-30%. And to make matters worse, what if you panicked and sold at the bottom and never got back in the stock market on its way to recovery? That’s why putting all your eggs in one asset class is dangerous.
Even though I’m relatively diversified by including real estate in my portfolio, I was certainly very scared by the stock market correction earlier this year. However, knowing that real estate doesn’t always move in the same direction as the stock market, I felt reassured that my cash flow wouldn’t necessarily be impacted. In fact, perhaps due to a bit of luck (or maybe solid upfront analysis on my properties), none of my tenants have skipped rent so far.
Stability
Most of us were taken by surprise by the stock market crash in March this year. It was terrifying to see how quickly and violently the market swung from all-time highs to a Bear MarketA prolonged market downturn where stock prices drop by 20% or more from recent peaks, typically accompanied by widespread investor pessimism and economic slowdowns.. Real estate, on the other hand, tends to be much more stable. It’s usually expensive and illiquid, so buying and selling physical property takes time and lots of money. There aren’t millions of shares of a single property being traded on an exchange like stocks are, so real estate prices fluctuate much slower and with less volatility.
Lastly, because real estate is a relatively illiquid asset, it’s difficult to quickly sell your investment. Sure, that can be seen as a negative, too. But I think too many people make emotion-based decisions when it comes to investing. How many times have you sold a stock because it earned you a quick buck but then regretted it a few months later as you watched the stock continue to rise? I know I have. Real estate, in a way, forces investors to keep their investments for much longer periods of time. And by doing so, it’s also much more likely for real estate investors to take advantage of Long-Term Capital GainsProfits earned from selling assets you owned for longer than one year, which are taxed at preferential rates (0%, 15%, or 20%) rather than standard paycheck income tax rates..
Tax Benefits
Any and every expense incurred by your property can be considered a loss and, therefore, act as write-offs against your profits. For example, you can deduct your mortgage interest, property taxes, insurance, HOA fees, utilities, cable bill, water bill, maintenance work, appliance replacements, gardening, fees incurred during the purchase and sale of the property, etc. All of those expenses really add up, especially in your early years of owning the property since your mortgage payments have a higher interest payment than the principal (for more on this, see how mortgage amortization works).
Physical property deteriorates and requires maintenance over time. Therefore, through a process called depreciation, the IRS allows real estate investors to deduct a portion of the property’s value from their profits every year. This typically amounts to a substantial write-off against your rental income.
When you sell an investment property, the IRS allows you to defer those capital gains through a process called a 1031 ExchangeA real estate rule that lets you sell an investment property and roll the full sale proceeds into a new property while postponing all capital gains and depreciation recapture taxes.. To qualify and take full advantage of a 1031 exchange, you must buy a similar property of equal or greater value. So if you had $250K in capital gains from your 1st property, doing a 1031 exchange on the property will allow you to defer paying taxes on those gains until you sell the property you rolled your money into. However, when you sell your 2nd property, you can do another 1031 exchange and roll your money into a 3rd property and so on and so forth. The ideal way to take advantage of this process is to keep 1031’ing until you die, because once you pass, your heirs will inherit your property with a Stepped-Up BasisA tax benefit where the cost basis of inherited assets (like real estate or stocks) resets to fair market value on the day the owner passes away, wiping out all capital gains taxes earned during their lifetime.. So unless you happen to pass on more than the current $23.16 million estate and gift tax exemption limit, your heirs could immediately sell the inherited property and pay $0 in capital gains!
Lastly, this article is largely focused on rental properties, but I wanted to briefly mention one tax benefit of home ownership called Home Sale Tax ExclusionA tax break allowing you to pocket up to $250,000 in capital gains ($500,000 for married couples) tax-free when selling your primary residence, as long as you lived in it for at least 2 of the past 5 years.. If you live and own your primary residence for 2 of the past 5 years, $250K of proceeds from the sale of your home will be exempt from taxes; if you’re married, that exemption doubles to $500K! So if you’re married, purchased a home for $500K, and sold it for $1M two years later, your $500K profit would be tax free. Additionally, if you used your home as a rental property for 3 of the past 5 years but lived in it for 2 of them, you still qualify for the exclusion.
Leverage
In real estate, you can leverage other people’s money, which means you can borrow or take out loans. Typically, you put in 25% of your money into a rental property, while the other 75% comes from a loan. That’s great because if I had $100K to invest, I can purchase a $400K rental property. When my rental property appreciates, it still appreciates with respect to the $400K market value, not the 25% that I invested. So if my $400K property appreciates 10% to $440K, my $100K investment grows 40% (from the $40K in appreciation). Essentially, leverage allows my $100K investment to grow 4x as much compared to if I didn’t leverage at all.
A non-leveraged real estate purchase would mean an all-cash purchase. While there are certain circumstances in which it might be beneficial to purchase a property with all cash, it’s not the norm. From a tax perspective, one downside of going all-cash (aside from Opportunity CostThe potential return or benefit you give up by choosing one financial option over another, like the future compound investment returns lost when spending money today.) is that you don’t have a loan. And when you don’t have a loan, you don’t get to deduct interest paid on that loan against your profits.
Cash Flow
As I’ve mentioned in my About page, one big focus of my investment strategy is to gain high cash flow, enough to easily cover my annual expenses. To achieve that, I am a strong believer in using rental properties.
When most people refer to stocks with solid, consistent dividend payouts, they’re usually referring to Dividend Aristocrats, companies that have paid and increased their dividend payouts every year for the past 25 consecutive years. And while that’s certainly an impressive track record, the typical dividend yield is somewhere between 2-4%. When I think about a good investment property, it usually yields anywhere between 8-15% ROI (return on investment). That entire return is paid out to me monthly since tenants pay on a monthly basis. Had I invested in Dividend Aristocrats instead, my cash flow would be negatively impacted in two ways: (1) I would only get paid quarterly because dividends are usually paid out quarterly, not monthly as it is via rental properties, and (2) my cash flow gets trimmed by 50-75%. Ouch!
Tangibility
To me, there’s just something about owning physical real estate that gives me a stronger sense of ownership - that my investments are real and truly exist. Real estate has an intrinsic value to it. No matter how good or bad the market is doing, the physical property will always have some monetary value.
Conclusion
Real estate investing has so many benefits that most other asset classes don’t have, especially with respect to taxes and cash flow. That said, I am very much invested in the stock market, as well (see my retirement allocation). If you learned a thing or two from this post, be sure to subscribe below so you don’t miss out on my coming article on the many benefits of investing in stocks, as well the risks and tradeoffs of investing in real estate.
Ultimately, I believe in a balanced approach to investing, so putting all my eggs in one basket (i.e. in one asset class) is something I avoid. For me, achieving financial freedom will be accomplished by building a portfolio of both stocks and real estate.
To run the numbers on a deal, use the free Real Estate Evaluation Tool or compare payoff options with the Mortgage Recast vs. Refinance calculator.
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Download the Homeowner Wealth & Mortgage Optimization Playbook
A one-page educational reference on home equity, mortgage decisions, and rent-versus-buy considerations.
- ✓ Rent versus buy considerations
- ✓ Mortgage payoff and recast concepts
- ✓ Home equity and opportunity cost notes
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this reference handy for future planning!
Your Next Step & Related Guides
View all resources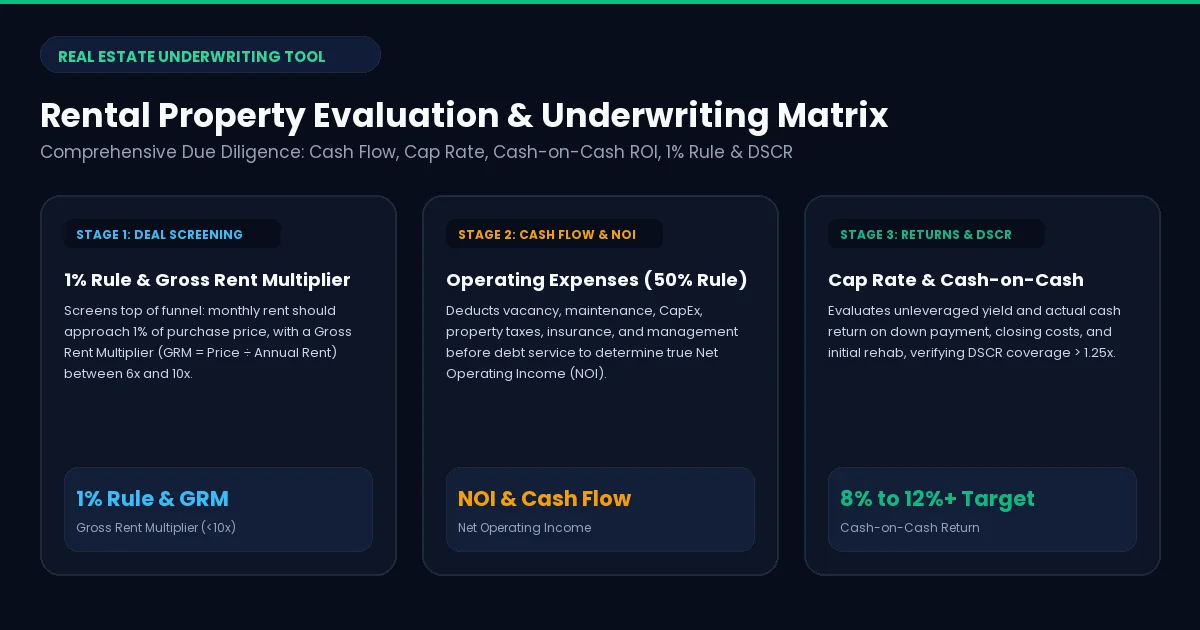
Real Estate Evaluation Tool
Screen rental properties with cash-on-cash return and cap rate.
Risks and Tradeoffs of Real Estate Investing
In my past post, 6 Reasons Why I Invest In Real Estate to Build Wealth, I talked about the many benefits of investing in real estate. However, it’s important to highlight the risks
How the Rich Create Generational Wealth Through Real Estate
Discover how the wealthy use 1031 exchanges, depreciation, and the step-up in basis to pass down real estate and build generational wealth tax-free.
Discussion 🟢 Open for Discussion 0