
Listen to Full Article
ReadyFull article audio (5 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: How To Set Up a Mega Backdoor Roth With Vanguard
Mega Backdoor Roth Decision Tree & Math Matrix
A 1-page visual guide to after-tax 401(k) space calculations, employer match buffers, and automated conversion protocols.
- ✓ 2026 total cap ($71,000) vs. match buffer worksheet
- ✓ Vanguard my.vanguardplan.com auto-conversion steps
- ✓ Pro-rata after-tax earnings checklist
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this checklist handy for retirement and tax planning!
Step 1: Verify After-Tax & Conversion Support
Log into my.vanguardplan.com (Vanguard's retirement plan portal, separate from personal brokerage) or check our Employer 401(k) Benefits Directory. Under Contributions, confirm your employer plan lists an After-Tax box alongside Pre-Tax and Roth.
Step 2: Set Your After-Tax Contribution Percentage
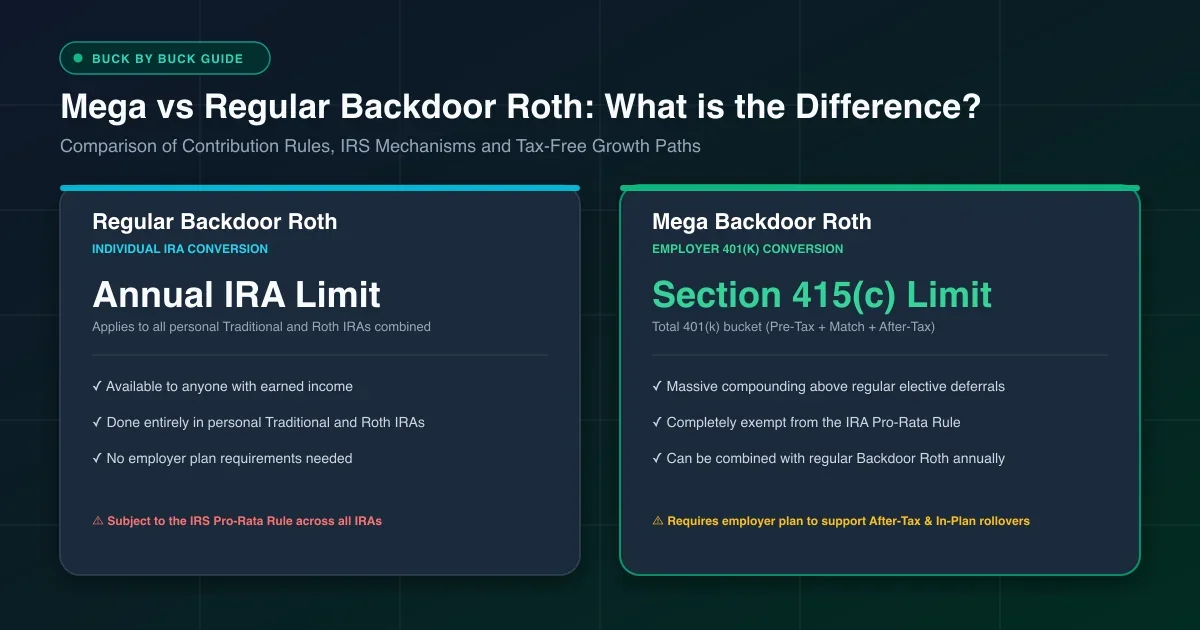
In 2026, total combined employee + employer + after-tax contributions cannot exceed $71,000 (if under age 50). Use the Mega Backdoor Roth Calculator to ensure your combined payroll percentage leaves full room for every dollar of employer match before maxing out.
Step 3: Activate Automatic In-Plan Roth Conversions
- Navigate to Manage Money → Contributions (or look for the banner labeled Convert After-Tax Money to Roth).
- Select Automatically convert future after-tax contributions so payroll deposits convert on settlement day with minimal taxable growth.
- If your plan does not expose the self-serve switch online, call Vanguard Participant Services (800-523-1188) and ask whether your plan allows automated sweeps or periodic phone in-service rollovers to your personal Vanguard Roth IRA.
Step 4: Mind Existing After-Tax Earnings & Form 1099-R
If you built up an unconverted after-tax balance in previous years, Separate Account Tracking Employer plans track your after-tax basis separately from your pre-tax 401(k), meaning converting only the after-tax sub-account applies pro-rata only to gains inside that sub-account. means you only owe ordinary income tax on the investment earnings inside your after-tax bucket, reported on IRS Form 1099-R in January.
Frequently Asked Questions
Quick answers to common questions, technical edge cases, and tax rules.
Does Vanguard allow automatic Mega Backdoor Roth conversions in 401(k) plans?
Yes, for employer plans that enable the feature. Inside Vanguard Institutional (my.vanguardplan.com), eligible plans offer a self-serve "Convert After-Tax Contributions Automatically" toggle right on the Contributions or After-Tax Balance screen, sweeping payroll contributions into the Roth 401(k) source the same day they post.
What phone number do I call for a Vanguard 401(k) Mega Backdoor Roth conversion?
Call Vanguard Participant Services at 800-523-1188 (Monday through Friday, 8:30 AM to 9:00 PM ET) if your plan requires phone authorization for In-Plan Roth Conversions or in-service distributions of after-tax balances.
Should I roll Vanguard after-tax 401(k) money into a Roth 401(k) in-plan or out to a Roth IRA?
An automated In-Plan Roth Conversion into your Vanguard Roth 401(k) is usually faster and hands-free every paycheck. An external rollover to a Vanguard Roth IRA offers broader ETF choices and lets you withdraw converted basis earlier under Roth ordering rules if needed.
What happens if my Vanguard after-tax contributions have earnings before I convert them?
Every conversion out of an after-tax 401(k) sub-account triggers a pro-rata split between non-taxable principal basis and taxable investment gains. Turning on Automatic In-Plan Roth Conversion keeps gains near $0 on each payroll cycle.
 Buck by Buck
Discussion 0
Author replies within 24h