
Listen to Full Article
ReadyFull article audio (5 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: How To Set Up a Backdoor Roth IRA With Vanguard
Backdoor Roth IRA Execution Flowchart
A 1-page visual checklist covering non-deductible contributions, pro-rata rule safeguards, and Form 8606 reporting.
- ✓ Dec 31 pro-rata check before converting
- ✓ Vanguard VMFXX settlement hold & conversion navigation
- ✓ Form 8606 non-deductible basis audit checklist
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this checklist handy for retirement and tax planning!
Pre-Flight Check: Confirm $0 in Other Pre-Tax IRAs
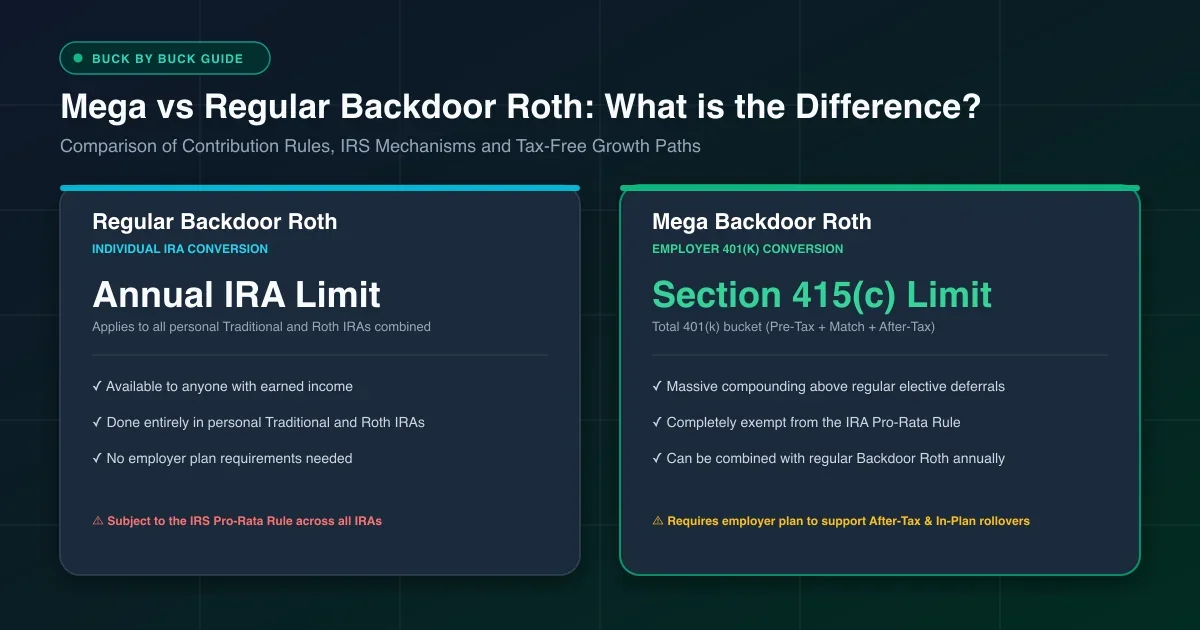
Before starting, verify that you hold $0 in any Traditional, Rollover, SEP, or SIMPLE IRA across every institution. Also double check whether your workplace 401(k) supports our Vanguard Mega Backdoor Roth Guide for even more tax-free space.
Step 1: Deposit Into Vanguard Traditional IRA (VMFXX)
- Open (or verify) both a Vanguard Traditional IRA and a Vanguard Roth IRA.
- Select Transact → Contribute to IRA and transfer up to $7,500 ($8,600 if 50+) for 2026.
- Leave your deposit in Vanguard's default settlement fund (
VMFXX) and wait 2 to 7 business days for the external bank hold to release.
Step 2: Click “Convert to Roth IRA”
- Open your Vanguard Traditional IRA summary card.
- Click Balances & Holdings (or More actions → Convert to Roth IRA).
- Select your destination Vanguard Roth IRA, choose Convert 100% of Settlement Fund (VMFXX), elect 0% federal/state tax withholding, and submit.
Step 3: Invest, Sweep VMFXX Pennies & File Form 8606
Because VMFXX earns money market yield daily during the bank hold, a few dollars of accrued dividend yield typically deposit on the 1st business day of the next month. Log back in once, click Convert to Roth IRA a second time to empty that trailing yield into your Roth IRA, invest into VTI or VTSAX (Vanguard Auto-Investing Guide), and document your basis on IRS Form 8606.
Frequently Asked Questions
Quick answers to common questions, technical edge cases, and tax rules.
Why does Vanguard leave a few dollars in my Traditional IRA after a Backdoor Roth conversion?
Vanguard sweeps uninvested Traditional IRA cash into VMFXX (Vanguard Federal Money Market Fund), which accrues daily dividend interest and pays out at month-end. Because converting mid-month creates $1 to $25 of accrued VMFXX yield that settles on the 1st of the following month, simply log back in next month and click "Convert to Roth IRA" a second time to sweep the pennies cleanly.
How long is Vanguard's settlement hold before converting to Roth IRA?
External checking deposits typically take 2 to 7 business days (often 7 calendar days for new bank links) before Vanguard marks the funds "Available to withdraw / convert" and unlocks the "Convert to Roth IRA" button.
Is there any tax penalty for converting VMFXX interest dividends to a Roth IRA?
No penalty applies. You will owe ordinary income tax only on the tiny dollar amount of VMFXX gains above your non-deductible basis (e.g., $2 to $15 adds roughly $1 to $5 to your tax bill), and sweeping it leaves your Traditional IRA cleanly at $0 on December 31.
Where is the Convert to Roth IRA button on Vanguard's new dashboard?
Open your Traditional IRA summary page, click "More actions" (or Balances & Holdings), and click "Convert to Roth IRA". Choose to convert 100% of your VMFXX settlement fund directly into your existing Vanguard Roth IRA.
 Buck by Buck
Discussion 0
Author replies within 24h