
Listen to Full Article
ReadyFull article audio (5 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: How To Set Up a Backdoor Roth IRA With Charles Schwab
Backdoor Roth IRA Execution Flowchart
A 1-page visual checklist covering non-deductible contributions, pro-rata rule safeguards, and Form 8606 reporting.
- ✓ Pre-conversion Traditional/SEP/SIMPLE IRA zero-out check
- ✓ Schwab Move Money conversion navigation path
- ✓ IRS Form 8606 Line 1-18 reporting map
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this checklist handy for retirement and tax planning!
Pre-Flight Check: Confirm Zero Pre-Tax IRA Balances
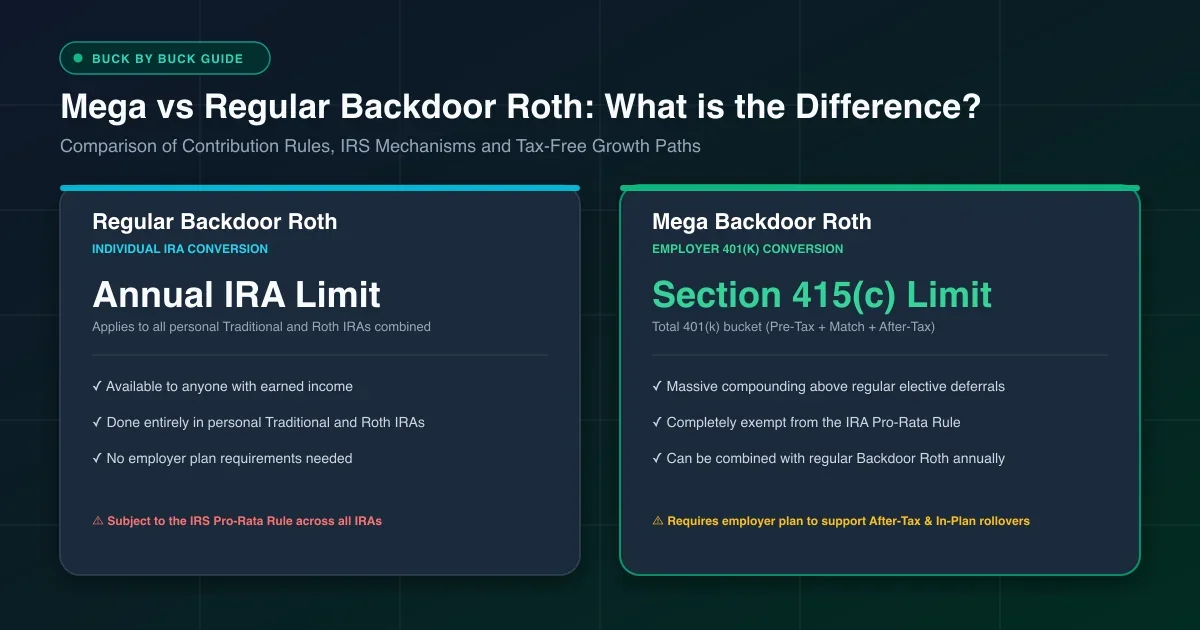
Before initiating a deposit, check every Traditional IRA, Rollover IRA, SEP IRA, and SIMPLE IRA titled under your Social Security Number (across Schwab and any outside custodian). If you hold pre-tax Rollover IRA money, consider doing a reverse rollover into your current employer 401(k) prior to December 31 so your Backdoor conversion stays tax-free. Need extra tax-free 401(k) room too? Pair this with our Schwab Mega Backdoor Roth Guide.
Step 1: Contribute to Your Schwab Traditional IRA
- Make sure you have both a Schwab Traditional IRA and a Schwab Roth IRA open (they take two minutes to open with $0 minimums).
- Go to Move Money → Online Transfer (or External Transfer) and deposit up to $7,500 ($8,600 if 50+) for 2026.
- Leave the money in cash while it settles. Do not purchase
SWVXXor index funds inside the Traditional IRA, as selling shares creates extra settlement delays.
Pro tip: Transferring settled cash from an existing Schwab Taxable Brokerage account into your Traditional IRA settles almost immediately instead of waiting 4 business days for an external bank hold!
Step 2: Convert Online to Your Schwab Roth IRA
- Once cash shows as settled/available (~4 business days for bank ACH), open Move Money → Transfers & Payments → Online Transfer.
- Select From: Traditional IRA and To: Roth IRA. Schwab automatically prompts the Roth Conversion election form inline.
- Choose Convert Full Balance / Transfer Specific Cash Amount, pick Do NOT withhold taxes (so 100% reaches the Roth IRA), and confirm the submission.
Step 3: Invest, Sweep Pennies & File Form 8606
- Invest immediately in Roth IRA: Buy your target index portfolio inside the Roth IRA (see our Schwab Auto-Investing Guide for fund choices like
SWTSXorVTI). - Sweep residual pennies: Check the Traditional IRA balance around the 1st of next month. If a few cents of sweep interest credited, click Transfer again to sweep them into your Roth IRA so it closes at $0.
- File IRS Form 8606: Report your non-deductible basis cleanly on Form 8606 alongside your tax return so you are never double-taxed on conversion.
Frequently Asked Questions
Quick answers to common questions, technical edge cases, and tax rules.
How long does cash take to settle before doing a Backdoor Roth conversion at Charles Schwab?
If you contribute via external bank ACH transfer into your Schwab Traditional IRA, Schwab typically places a 4-business-day settlement hold on those funds before online Roth conversion transfers become eligible. Transferring settled cash from an existing Schwab brokerage account clears almost immediately.
Should I keep my Charles Schwab Traditional IRA open with $0 after converting?
Yes. Leave your Schwab Traditional IRA open at $0 balance rather than closing it so next year's Backdoor Roth contribution takes one minute. Having $0 across all Traditional, SEP, and SIMPLE IRAs on December 31 avoids the pro-rata tax trap.
How do I convert residual interest pennies in a Schwab Traditional IRA?
Because Schwab's bank sweep earns tiny monthly interest while your deposit waits to clear, check your Traditional IRA early the following month. If $0.05 to $1.00 of residual interest lands, simply run a second online Transfer to your Roth IRA so your balance returns to $0.
What is the 2026 Backdoor Roth IRA contribution limit at Schwab?
In 2026, the annual IRA contribution limit is $7,500 if you are under age 50 (or $8,600 if age 50+). There is no cap on how much you can convert to Roth, only on your annual non-deductible contribution.
 Buck by Buck
Discussion 0
Author replies within 24h