
Listen to Full Article
ReadyFull article audio (6 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: How To Set Up a Mega Backdoor Roth With Charles Schwab
Mega Backdoor Roth Decision Tree & Math Matrix
A 1-page visual guide to after-tax 401(k) space calculations, employer match buffers, and automated conversion protocols.
- ✓ Exact 2026 total cap vs. match buffer calculation
- ✓ Schwab Workplace phone request script
- ✓ In-plan Roth vs. external Roth IRA rollover rules
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this checklist handy for retirement and tax planning!
Step 1: Verify Your Schwab 401(k) Plan Supports Both Gates
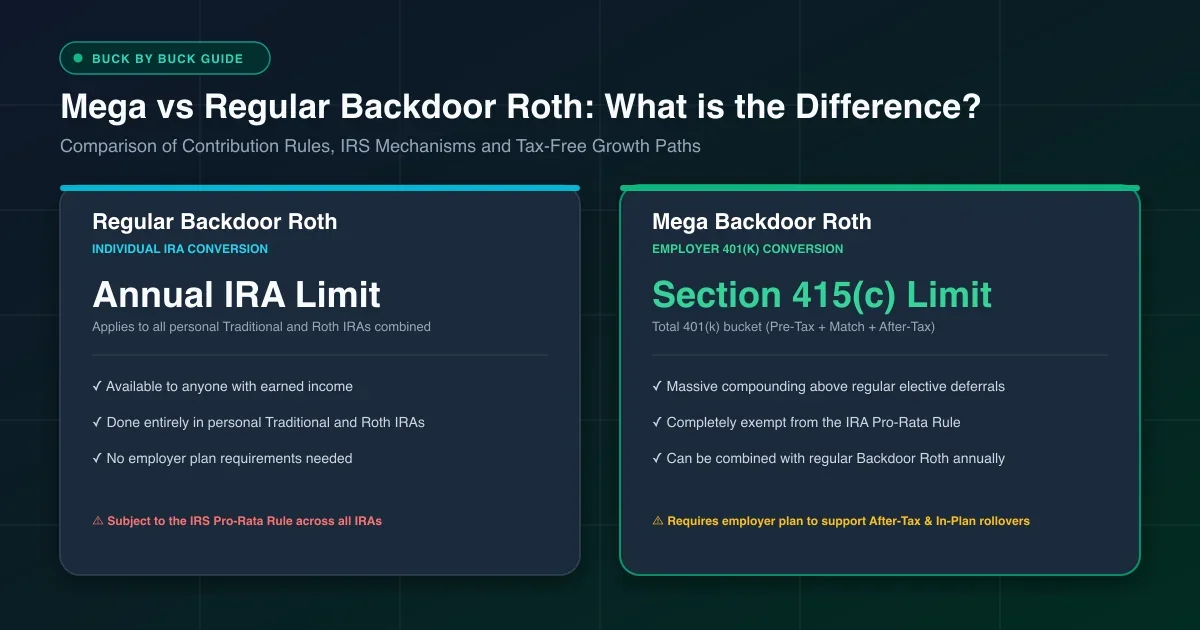
Unlike IRAs, Mega Backdoor Roth rules are controlled entirely by your employer's plan document. Check our crowdsourced List of 401(k) Benefits by Company or log into workplace.schwab.com and verify:
- After-Tax Payroll Deferrals: Under Manage → Contributions, confirm there is a distinct percentage input labeled After-Tax (separate from Pre-Tax and Roth 401(k)).
- Conversion Exit Path: Open your Summary Plan Description (SPD) under Plan Documents and confirm either In-Plan Roth Rollovers or In-Service Non-Hardship Withdrawals are enabled for after-tax money.
Step 2: Calculate Room & Set After-Tax Contributions
Run your paycheck numbers through our Mega Backdoor Roth Calculator first so you do not inadvertently crowd out any employer match dollars. For 2026, the total combined cap (under age 50) is $71,000.
Inside Manage → Contributions on Schwab Workplace, divide your remaining after-tax room across your remaining paychecks and set the After-Tax % carefully.
Step 3: Convert After-Tax Dollars Immediately
Leaving cash inside the After-Tax bucket allows investment earnings to grow—and those pre-conversion gains are taxed as Ordinary Income Income taxed at your top marginal federal and state income tax bracket, unlike the tax-free growth earned once money sits inside the Roth bucket. when converted. Always automate or convert right away:
- Option A (Online Auto-Convert): If your Schwab plan displays an Automatic In-Plan Roth Conversion toggle on the Contributions or Rollover screen, enable it once. Every future after-tax paycheck converts cleanly on settlement.
- Option B (Phone Setup at 800-724-7526): If the toggle is absent online, call Schwab Workplace Financial Services at 800-724-7526. Ask the representative: "Can you please set up an automatic recurring in-plan Roth conversion for my after-tax 401(k) contributions, or verify my plan's manual rollover cadence?"
Step 4: Invest via Core Index Menu or Schwab PCRA
Many Schwab employer 401(k) plans feature a Schwab PCRA Personal Choice Retirement Account: a self-directed brokerage window linked inside select Schwab 401(k) plans giving access to broader ETFs and mutual funds. window. After your funds move to the Roth bucket, either invest in your core institutional S&P 500 index fund or sweep converted dollars into PCRA to mirror your broader portfolio. If your employer allows in-service rollovers to an external Roth IRA instead, check our Schwab Backdoor Roth IRA Guide for managing a personal Schwab Roth IRA cleanly.
Frequently Asked Questions
Quick answers to common questions, technical edge cases, and tax rules.
Can you set up an automated Mega Backdoor Roth inside a Charles Schwab 401(k)?
Yes, if your employer 401(k) plan at workplace.schwab.com permits both After-Tax contributions and either automated In-Plan Roth Conversions or in-service distributions. Some Schwab employer plans support online automated conversions, while others require calling Schwab Workplace Services at 800-724-7526.
What is the phone number for Charles Schwab 401(k) Mega Backdoor Roth conversions?
Call Schwab Workplace Financial Services at 800-724-7526 (or the plan-specific number shown inside workplace.schwab.com) and request either an automated recurring In-Plan Roth Rollover or an in-service withdrawal of your after-tax balance to a Schwab Roth IRA.
Can I use a Charles Schwab PCRA (Personal Choice Retirement Account) for Mega Backdoor Roth funds?
Yes, if your employer plan includes a Schwab PCRA self-directed brokerage window. Once your after-tax dollars convert into the Roth 401(k) bucket, PCRA allows you to invest converted Roth funds in almost any ETF or index fund rather than being restricted to your core 401(k) menu.
How much after-tax space is available in 2026 under Charles Schwab 401(k) rules?
Total combined contributions (your pre-tax/Roth employee deferrals + employer match + after-tax contributions) are capped at $71,000 in 2026 (or higher with catch-up eligibility if age 50+). Subtract your $24,000 standard deferral and your employer match to find your exact remaining after-tax room.
 Buck by Buck
Discussion 0
Author replies within 24h