
What's A Mega Backdoor Roth?
Listen to Full Article
ReadyFull article audio (12 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: What's A Mega Backdoor Roth?
If you like your Roth IRA for its tax-free growth, you’re really going to like a Mega Backdoor RothA strategy that lets you supercharge your retirement savings by putting after-tax dollars into your employer 401(k) beyond the standard limit, then rolling them into a Roth 401(k) or Roth IRA.! Contributions to a Roth IRA are funded with after-tax dollars and earnings grow entirely tax-free. Similarly, a mega backdoor Roth is also funded with after-tax dollars and earnings grow tax-free but with a much higher contribution limit!
Roth IRA and 401(k) Limits for 2026
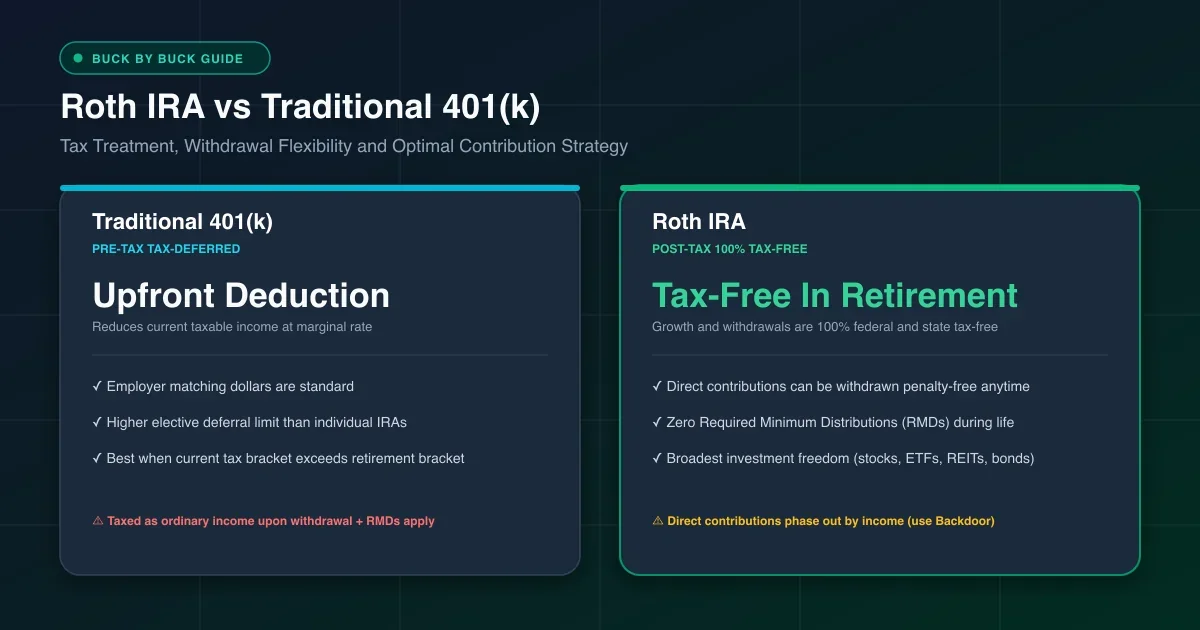
Before we learn more about the mega backdoor Roth, it’s important to understand the tax benefits and differences between a Roth IRA and a 401(k), their income restrictions, and their contributions limits. If you’ve read my Roth IRA or 401(k) post, you’ll know that the only reason to consider a Backdoor Roth IRAA simple two-step workaround for high earners who make too much to contribute to a Roth IRA directly: you deposit after-tax cash into a Traditional IRA and immediately convert it to a Roth IRA. is if your income exceeds a certain threshold. Performing a Backdoor IRA conversion works around those income restrictions and allows anyone in any tax bracket to max out a Roth IRA with $7,500 in after-tax dollars. For those 50 or older, the catch-up limit is $1,100, so contributions max out at $8,600.
As long as your employer offers a 401(k) plan, anyone can contribute to a 401(k), regardless of your income level. Employees have an elective deferral limit of $24,000 as of 2026. Thankfully, employer match contributions don’t count toward that limit, but there is a combined employee + employer 401(k) contribution limit of $71,000 under IRS Section 415(c). For those 50 or older, the catch-up limit is $8,000, bringing the total employee + employer 401(k) contribution limit to $79,000.
It’s an understatement to say that the combined employee + employer 401(k) contribution limit of $71,000 is quite high. So that begs the question, “How does anyone ever reach those limits?” Well, there are two ways, but only one of them can realistically get you there.
Employer Match Contributions
Employees can contribute up to $24,000 of the combined max of $71,000. That leaves a max headroom of $47,000 for combined employer matching and after-tax contributions. However, most employers don’t even get close to contributing the full amount. A good match is typically around 4% of your base salary. So reaching the 401(k) cap with employer contributions alone is rarely possible.
For example, let’s say you make $150,000, max out your 401(k) with $24,000 of your pre-tax dollars, and your employer match contribution is 100% of your 401(k) contributions, up to 4% of your base salary. That would look like:
Employee contribution: $24,000
Employer match: $150,000 x 4% = $6,000
Total 401(k) contributions: $24,000 + $6,000
Subtracting employer contributions and pre-tax elective deferrals from the max 401(k) contribution limit of $71,000 leaves significant remaining space, which is why employer match contributions won’t realistically be enough to help you reach the combined max. Luckily, if your employer’s 401(k) plan allows after-tax contributions, you can do a mega backdoor Roth to make up the remainder!
Mega Backdoor Roth
Before diving into how to do a mega backdoor Roth, there are some prerequisites and considerations to highlight:
Your employer’s 401(k) plan needs to allow after-tax contributions. Without this option, you can’t do a mega backdoor Roth. Check with your employer’s HR team to find out if they offer this benefit.
Your employer’s 401(k) plan allows for “in-service” withdrawals to a Roth IRA or “in-plan” rollovers to a Roth 401(k). If neither is offered, you can’t touch your after-tax contributions in your 401(k). Therefore, your earnings would grow tax-deferred, not tax-free! In that case, I’d recommend avoiding the mega backdoor Roth altogether. It’s actually worse to invest after-tax dollars in a 401(k) than a regular brokerage account because 401(k) withdrawals are taxed as ordinary income, not (long-term) capital gains!
If you haven’t maxed out your 401(k) with pre-tax dollars, do that first.
No matter what your income is, you can do a mega backdoor Roth. There’s no minimum contribution amount, but there is a max.
In order to max out a mega backdoor Roth, you need to have a relatively high income. Why? Because maxing out a mega backdoor Roth would require up to $47,000 of post-tax dollars. That’s what puts the “mega” in mega Backdoor Roth! Its younger sibling, the backdoor IRA, maxes out at $7,500.
On the last point, remember that we’re trying to utilize the combined employee + employer 401(k) contribution limit of $71,000. If your employer contributes $6,000 to your 401(k), for example, your total contributions (pre-tax + post-tax dollars) would come out to the full limit. To model your exact numbers, use our interactive 2026 Mega Backdoor Roth Calculator.
| Gross Income | $150,000 |
|---|---|
| Pre-tax 401(k) contributions | ($24,500) |
| Income after 401(k) contributions | $125,500 |
| Federal standard deduction (single) | ($16,100) |
| Federal taxable income | $109,500 |
| FICA TaxesFederal payroll taxes consisting of Social Security (6.2%) and Medicare (1.45%) levied strictly on W-2 wage and active self-employment earnings, never on capital gains, dividends, or retirement distributions. (6.2% Social Security tax, 1.45% Medicare tax) | ($8,369) |
| 2026 Federal taxes (13.73% effective tax rate) | ($13,514) |
| After-tax 401(k) contributions | ($41,500) |
| Take-home income | $125,500 - (taxes) - (after-tax 401(k) contributions) = $62,117 |
So in this scenario, a single filer making $150,000 annually who maxes out their traditional 401(k) with both pre-tax and post-tax dollars is only left with $62,117 assuming no state taxes and before expenses!
Alright, now let’s finally talk about how to do a mega backdoor Roth. First, you’ll need to reconfigure your 401(k) contributions with your brokerage firm so that it not only contributes pre-tax dollars towards your traditional 401(k), it now needs to contribute after-tax dollars towards, too. Remember that if you’re just starting to contribute post-tax dollars partway through the year and want to max out your mega backdoor Roth, the math isn’t as simple as ($72,000 - $24,500 - employer match contributions) divided by (# of paychecks in a year); instead of dividing by (# of paychecks in a year), it now becomes (# of remaining paychecks this year), which can amount to a massive reduction in take-home pay.
Now that you’re contributing after-tax dollars to your 401(k), there’s really only 1 more step. As I mentioned in point #2 in the prerequisites above, your 401(k) needs to allow for “in-service” withdrawals to a Roth IRA or “in-plan” rollovers to a Roth 401(k):
In-service withdrawals: This would require you to manually call your 401(k) brokerage firm, like Fidelity or Vanguard, every time you want to convert your after-tax dollars to your Roth IRA.
In-plan rollovers: This is the much simpler approach to setting up a mega backdoor Roth. You only have to call your brokerage firm, like Fidelity or Vanguard, one time and have them set up automatic rollovers of your 401(k) after-tax contributions into your Roth 401(k). So as soon as your contributions are taken from your paycheck and land in your 401(k), they’ll automatically get rolled into your Roth 401(k).
To summarize the two options:
| In-Service Withdrawals to a Roth IRA | In-Plan Rollovers to a Roth 401(k) |
|---|---|
| Hands-on approach | Hands-off approach |
| Requires calling brokerage firm every withdrawal | One-time setup |
| Manual process may lead to accrued earnings in 401(k), requiring you to pay taxes on earnings when you withdraw | Automatic approach avoids 401(k) earnings before the conversion, thereby avoiding having to pay any taxes on each rollover |
| Large range of investment options | Limited by your employer's 401(k) investment options |
That’s it. Now you know how to do a mega backdoor Roth and can watch your earnings grow tax-free!
One last cautionary note before doing any backdoor Roth conversion: Be careful not to mix after-tax dollars with pre-tax dollars in retirement accounts, as you may be subject to tax consequences due to pro-rata rules. Talk to a professional if you need assistance.
Can I Do Both A Backdoor IRA and A Mega Backdoor Roth In The Same Year?
Yes, you can max out both a Backdoor Roth IRA and a Mega Backdoor Roth in the same tax year because they operate under completely separate IRS provisions. A regular Backdoor IRA utilizes annual individual retirement arrangement limits ($7,500 in 2026, plus $1,100 if age 50 or older), whereas a Mega Backdoor Roth utilizes employer-sponsored 401(k) limits under IRC Section 415(c) ($71,000 in 2026, plus $8,000 if age 50 or older). Funded together, an individual can shelter up to $78,500 (or $87,600 if 50+) into tax-free Roth growth annually.
Summary of Income and Contribution Limits for 2026
As of 2026, the income and contribution limits for each type of retirement account are:
401(k):
No income restrictions
$24,000 elective deferral limit
$8,000 catch-up limit if 50 or older
Roth IRA:
Direct contribution phase-outs apply for high earners (use Backdoor Roth to bypass)
$7,500 contribution limit
$1,100 catch-up limit, if 50 or older
Mega Backdoor Roth:
No income restrictions
$47,000 max headroom for after-tax contributions plus employer matching under the $71,000 annual Section 415(c) ceiling.
It’s important to note that catch-up contributions to a 401(k) or Roth IRA don’t count toward their respective contribution limits. So the total combined contribution limits look like:
Combined Roth & 401(k) Ceiling (Under 50): $24,000 elective deferral + $47,000 after-tax space + $7,500 Roth IRA = $78,500
Combined Roth & 401(k) Ceiling (Age 50+): $78,500 + $8,000 401(k) catch-up + $1,100 IRA catch-up = $87,600
If you and your spouse work for employers with mega backdoor Roth options, you can double these figures to shelter substantial sums into compounding Roth wealth each year.
As I mentioned earlier, maxing out a mega backdoor Roth demands quite a high income, given how much you could potentially contribute. You obviously don’t need to completely max out your account, so do what you can. Also, if you’re considering a mega backdoor Roth, you probably need to do a regular backdoor IRA, too. You may want to max out that account first before doing the mega since it’s slightly more straightforward. Ultimately both options result in the same tax-free growth, so the choice is yours!
Mega Backdoor Roth Qualification & Decision Tree PDF
Visual decision flow mapping plan documents, in-service rollover mechanics, and paycheck contribution allocations without tax penalties.
Tools & Step-by-Step Guides
To help you implement this strategy, check out these resources:
2026 Mega Backdoor Roth Calculator: Calculate your exact remaining after-tax space, employer match deduction, and per-paycheck contribution schedule.
How to Set Up a Mega Backdoor Roth with Fidelity: Detailed walkthrough with screenshots on enabling automated in-plan conversions.
How to Set Up a Backdoor Roth IRA with Fidelity: Step-by-step guide on standard Backdoor Roth IRA conversions.
Mega vs. Regular Backdoor Roth: What's the Difference?: Side-by-side comparison matrix breaking down eligibility and tax mechanics.
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Frequently Asked Questions
Quick answers to common questions, technical edge cases, and tax rules.
Can I do both a Backdoor IRA and a Mega Backdoor Roth in the same year?
Yes. You can max out both in the same tax year because they utilize separate IRS limits: Backdoor Roth conversions apply to annual IRA limits ($7,500 in 2026), while Mega Backdoor Roth conversions utilize after-tax 401(k) limits up to the overall Section 415(c) additions cap ($71,000 in 2026).
What is the difference between an in-service withdrawal and an in-plan rollover?
An in-service withdrawal distributes after-tax 401(k) contributions out of your employer's plan directly into an external Roth IRA, which usually requires manual phone requests. An in-plan rollover automatically transfers after-tax 401(k) contributions into a designated Roth 401(k) bucket within the same employer plan upon each payroll deposit.
What are the Mega Backdoor Roth contribution limits for 2026?
In 2026, the IRS Section 415(c) overall 401(k) additions limit is $71,000 (or $79,000 if age 50 or older). After accounting for the $24,000 employee elective deferral and employer matching contributions, high earners can contribute up to $47,000 in after-tax funds.
Download the Executive Equity & Tax Optimization Playbook
A one-page educational reference covering equity compensation, retirement accounts, and tax-aware planning concepts.
- ✓ Equity compensation tax basics
- ✓ Account-type and bracket considerations
- ✓ Questions to bring to a tax professional
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this checklist handy for retirement and tax planning!
Your Next Step & Related Guides
View all resources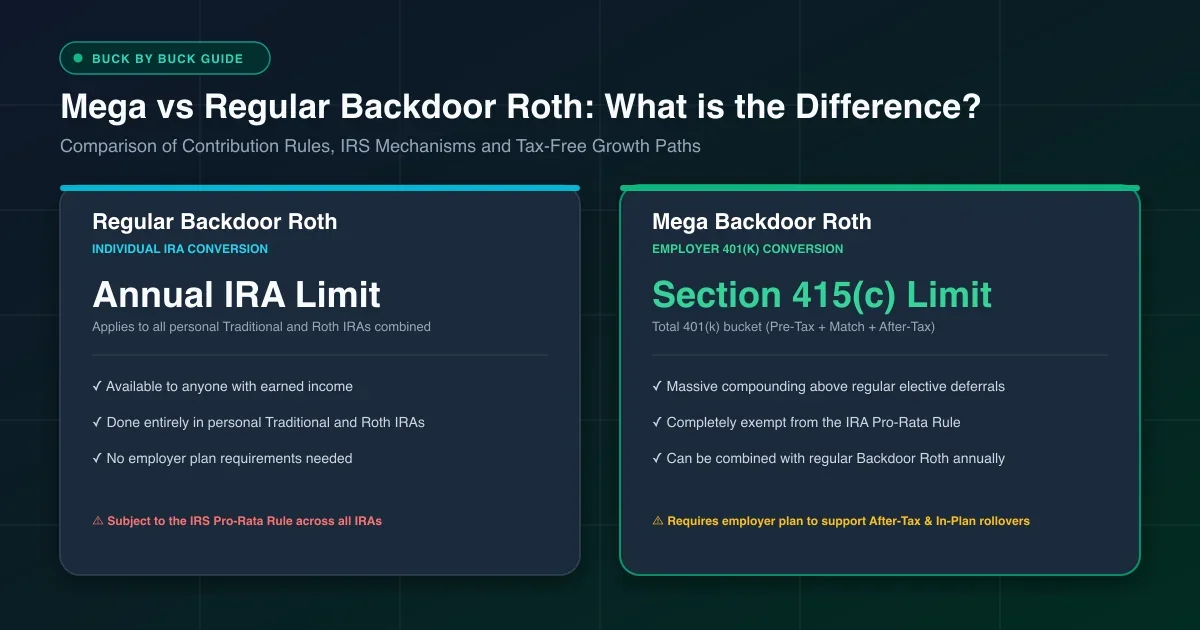
Mega Backdoor Roth Calculator
Estimate your remaining after-tax 401(k) contribution space.
Mega vs Regular Backdoor Roth: What's the Difference?
For high income earners, the Backdoor Roth conversion is a popular way to get around the income limits that prevent high earners from contributing directly to a Roth IRA. The Mega
Roth IRA or 401(k): Which One Is Right For You?
I hear it all the time, “Should I invest in a Roth IRA or a 401(k)?” To help you answer that question, first we need to know what they are and what some of their benefits are. From
Discussion 🟢 Open for Discussion 0