
Ultra-Rich Estate Strategies Demystified: What Billionaires Do vs. What High Earners Need
Listen to Full Article
ReadyFull article audio (18 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: Ultra-Rich Estate Strategies Demystified: What Billionaires Do vs. What High Earners Need
If you spend time in high-earner finance circles or read about advanced tax planning, you have probably seen plenty of buzz around ultra-rich estate strategies. People talk about GRATs, SLATs, dynasty trusts, family limited partnerships, and shifting assets out of reach of the tax authorities.
If you are a successful tech professional, corporate executive, physician, or entrepreneur with a balance sheet between $2M and $15M, it is easy to wonder: "Am I leaving millions on the table by not doing what the ultra-wealthy do?"
The short answer is almost certainly no. In fact, rushing into ultra-rich estate structures before your balance sheet genuinely demands it is one of the most expensive and regret-inducing mistakes high earners make. Today, we will demystify exactly how the ultra-rich shelter assets, expose the hidden traps of these vehicles, and walk through an actionable, net-worth-tiered roadmap so you know exactly what to do at each stage of your financial journey.
The Wealth Perception Gap: High Earners vs. Dynasty Capital
There is a fundamental difference between having a high income or a healthy nest egg and having multi-generational dynasty capital:
- The $2M to $10M High Earner: You built your wealth through high W-2 salaries, disciplined saving into low-cost index funds, company RSU equity, stock options, and primary home equity. You still rely on your portfolio for living expenses, future healthcare, and personal freedom. Maintaining full liquidity, asset control, and simple administration is paramount.
- The $50M+ Dynasty Family: Their primary residence, lifestyle spending, and retirement security are already guaranteed many times over. Their only financial enemy is the 40% federal estate tax on generational asset transfer. They are willing to sacrifice liquidity, surrender control, pay $30,000 annually in legal and accounting fees, and lock up assets forever just to avoid tax at death.
When high earners try to copy billionaire tactics, they often end up with the worst of both worlds: hefty legal bills, rigid irrevocable contracts, and tax headaches, all to solve an estate tax problem they do not actually have.
The Ultra-Rich Toolset Demystified (Without the Jargon)
Let us break down the four most common tools wealth advisors pitch to the ultra-rich, translated into plain English:
1. Grantor Retained Annuity Trusts (GRATs)
The Pitch: A GRAT is designed to pass aggressive asset growth to your children with zero gift tax.
How it works: You place a volatile, high-growth asset (such as early-stage private equity, pre-IPO tech stock, or commercial real estate) into a trust for a short period, typically two to five years. The trust is required to pay you back your original investment plus a modest government benchmark interest rate (known as the official hurdle rate). If the underlying stock explodes in value (say, rising 100% or 200%), your original capital plus the benchmark interest returns to you, while all the surplus profit transfers to your children completely free of federal gift or estate tax.
The catch: If the asset stays flat or drops in value during the trust term, the maneuver fails completely. You get your stock back, but you have lost the $10,000 to $20,000 spent on attorneys and valuation appraisers to set it up.
2. Spousal Lifetime Access Trusts (SLATs)
The Pitch: Use your massive federal lifetime exemption now to lock in tax-free compounding, while keeping indirect access to the cash through your spouse.
How it works: You (the donor spouse) make an irrevocable gift of cash, investment portfolios, or real estate into an independent trust naming your spouse (and children) as beneficiaries. Because you gave the assets away as a completed gift, the assets leave your personal taxable estate forever.
How the spouse spends the money: The trustee can distribute trust income or principal directly to your beneficiary spouse to cover reasonable health, education, maintenance, and support needs. Your spouse deposits those distributions into their personal checking account and uses them for normal household spending, vacations, or family living expenses. In this way, your household retains indirect access to the portfolio's cash flow.
Why this bypasses the joint estate: A common question is: "If my spouse receives money from the SLAT, doesn't it just get added back to our joint estate anyway?" The answer lies in how the trust is drafted. Under federal tax law, as long as your spouse does not have an unrestricted legal right to withdraw the entire trust balance or leave it to anyone they choose (known as a general power of appointment), the underlying trust principal is never included in your spouse's gross estate. The trust assets bypass your estate, bypass your spouse's estate, and eventually transfer directly to your children or grandchildren with zero estate tax, even if the portfolio has compounded from $15M to $60M.
The catches and risks: The word irrevocable is absolute. You cannot unwind the trust once created, and major life events can permanently sever your access:
- If your spouse dies first: Trust distributions to your spouse terminate instantly. The remaining trust assets pass directly down to the next beneficiaries (your children). As the surviving donor spouse, you are legally locked out. You cannot receive a single dollar for the rest of your life.
- In the event of divorce: Unless your estate attorney included a specialized "floating spouse" clause (defining the beneficiary spouse as whoever you are legally married to at any given time), your ex-spouse remains the trust's lifetime beneficiary. Your ex-spouse continues receiving distributions funded by your wealth, while you receive nothing.
- The reciprocal trust trap: You and your spouse cannot simply set up identical mirror SLATs for each other at the same time. Tax authorities apply the mutual trust doctrine to collapse both trusts, treating them as if you created them for yourselves and pulling all the assets back into your taxable estates.
3. Dynasty Trusts (Generation-Skipping Multigenerational Trusts)
The Pitch: Shield family wealth from the 40% federal estate tax not just when you die, but forever across your children, grandchildren, and great-grandchildren.
How it works: In standard estate planning, when you leave wealth to your children, any remaining assets in their hands are taxed again when they pass away if their estates exceed federal limits. Over three generations, repeated 40% estate taxes can confiscate over 75% of a family's legacy. A dynasty trust breaks this cycle.
You establish the trust in a state that has abolished the legal time limit on trusts (states like South Dakota, Nevada, Delaware, or Wyoming have no rule against perpetuities). You fund the trust using your lifetime estate exemption and allocate your generation-skipping transfer (GST) tax exemption. Because the trust never dies, its assets can compound across hundreds of years. Descendants can receive distributions for living expenses or education, yet the underlying principal is never subjected to estate tax at each generational transition.
The catch: Assets placed in a dynasty trust are permanently bound by the trust agreement. Beneficiaries cannot liquidate the trust, and you must hire and pay an institutional corporate trustee in that state, requiring $3,000 to $10,000+ in annual administration and tax compliance fees for generations.
4. Irrevocable Life Insurance Trusts (ILITs)
The Pitch: Life insurance payouts are income-tax-free, but they are NOT estate-tax-free if you personally own the policy at death.
How it works: An ILIT owns the policy instead of you. When you pass away, the death benefit pays out to the trust outside of your estate, providing instant cash liquidity for heirs to settle real estate estate taxes without being forced to sell family properties at fire-sale prices.
The catch: Life insurance for ultra-wealthy estate liquidity is expensive, and once the policy is inside the ILIT, you cannot borrow against its cash value or cancel it for personal cash.
The 3 Hidden Traps of "Playing Billionaire" Too Early
Before you sign up for sophisticated irrevocable trusts, consider the real-world friction that private wealth marketing glosses over:
Trap 1: The Fatal Loss of the Step-Up in Cost Basis
When you own an asset in your own name or inside a standard Revocable Living TrustA legal arrangement that holds ownership of your assets while you are alive, allowing everything to transfer to your beneficiaries immediately upon death without going through probate court., your heirs receive a full step-up in Cost BasisThe original money you paid for an investment plus reinvested dividends. When you sell, you are only taxed on your actual investment profits above this number, never on your original cash. at death. If you bought index funds or rental properties for $200,000 decades ago and they are worth $2,000,000 when you pass away, your children inherit them at a $2,000,000 basis. If they sell the next week, they pay $0 in capital gains tax.
When you gift assets into an irrevocable trust or SLAT during your life, the assets carry over your original low basis. By attempting to avoid an estate tax you might never owe, you might force your children to pay 20% to 37% in combined federal and state capital gains taxes when they sell.
Trap 2: Legal Drafting and Ongoing Accounting Drag
A revocable living trust costs $1,500 to $3,500 to draft and requires zero ongoing maintenance while you are alive. It uses your personal Social Security Number and files no separate tax returns.
Irrevocable trusts cost $15,000 to $35,000+ upfront in legal retainer fees. They require their own separate Employer Identification Number (EIN), separate annual fiduciary tax return filings (Form 1041), and professional accounting fees of $1,500 to $4,000 every single year for decades.
Trap 3: Inflexibility During Life Shocks
What happens if you experience a career burnout, a business failure, a long Bear MarketA prolonged market downturn where stock prices drop by 20% or more from recent peaks, typically accompanied by widespread investor pessimism and economic slowdowns., or an unexpected medical catastrophe? Assets held inside irrevocable shelters are out of your hands. Surrendering control of your wealth before your personal financial independence is rock-solid creates permanent vulnerability.
The Net Worth Reality Ladder: What to Do at Each Tier
Here is an unbiased, pragmatic framework categorizing exactly when to implement estate planning maneuvers based on actual household wealth:
Tier 1: Under $3M Net Worth (The Core Foundation)
Your Objective: 100% control, total liquidity, zero complexity, and ProbateA court-supervised process for validating a will, paying off debts, and distributing property after death. It can drag on for months or years, costs thousands in legal fees, and becomes public record. avoidance.
- Revocable Living Trust: Serves as the master container for your home and taxable brokerage accounts. Keeps your family private and avoids costly, public probate court. Explore our step-by-step Living Trust Brokerage Retitling Checklist.
- Pour-Over WillA backup will that scoops up any assets you forgot to put into your living trust while alive and transfers them into the trust after death.: Catches any stray assets left outside your trust and formally names legal guardians for minor children.
- Beneficiary Designations: Name primary and contingent beneficiaries on all 401(k), IRA, and HSA accounts. These designations bypass probate automatically.
- Durable Financial & Healthcare Powers of Attorney: Ensures your spouse or trusted partner can manage bills and medical decisions if you are incapacitated.
- Term Life Insurance & Umbrella Coverage: Stacking $2M to $5M of cheap term life and a $2M umbrella policy shields your family from unexpected loss and civil lawsuits.
Tier 2: $3M to $10M Net Worth (State Tax & Early Gifting)
Your Objective: Mitigate state-level estate tax cliffs, protect growing assets, and gift without tax friction.
- Mitigating State Estate Tax Cliffs: Federal estate taxes only apply to very large estates, but 12 states plus Washington D.C. levy separate state estate taxes with much lower exemptions:
- Oregon: Exemption starts at just $1.0M.
- Massachusetts: Exemption starts at $2.0M.
- Washington State: Exemption starts at $2.193M (with top state rates of 20%).
- New York: Exemption is around $7M, but features a notorious tax cliff: if your estate exceeds 105% of the exemption, you lose the exemption entirely and your estate is taxed from dollar one.
- Annual Exclusion Gifting: Gift up to $19,000 per recipient per year ($38,000 for married couples) to children or family members. When possible, gift highly appreciated assets (such as low-basis index funds or company stock) instead of cash, especially to adult recipients in a lower capital gains bracket, so you shift both the future growth and the built-in tax bill out of your estate without touching your lifetime exemption or triggering gift tax returns.
- 529 College Superfunding: Front-load up to $95,000 per child ($190,000 married) into a 529 plan in year one, taking advantage of 5-year gift acceleration rules. Check out our Child Investing Accounts Compared Guide.
Tier 3: $10M to $15M Net Worth (The Compounding Growth Trap)
Your Objective: Modeling future compound growth before it breaches federal thresholds.
This is the inflection point where high earners must pay attention. If you are 48 years old with $12M invested in broad-market index funds and real estate compounding at 7% per year, your portfolio will reach $23.6M in 10 years and over $46M in 20 years. Even with a generous married federal exemption, you are heading straight toward a 40% federal tax on all growth above the ceiling.
At this stage, you begin exploring pre-emptive growth-freezing maneuvers (like annual gifting of high-appreciation assets, family business restructuring, and initial SLAT evaluations) to prevent your future growth from compounding inside your taxable estate.
Tier 4: $15M to $30M+ Net Worth (Irrevocable Asset Freezing)
Your Objective: Removing future appreciation from your taxable estate forever.
- Spousal Lifetime Access Trusts (SLATs): Gifting high-growth assets into an irrevocable trust for your spouse locks in your lifetime exemption and ensures decades of asset compounding happen outside the 40% estate tax net.
- Grantor Retained Annuity Trusts (GRATs): Excellent for business founders or tech executives holding pre-IPO stock, concentrated RSU equity, or high-growth equity options (like Netflix SOP). Siphons explosive growth to children gift-tax-free.
- Dynasty Trusts: Established in trust-friendly states (like South Dakota, Delaware, or Nevada) with no rule against perpetuities, allowing wealth to compound tax-free for multiple generations.
The Top Annual Moves Anyone Can Use (Without a $20,000 Lawyer)
You do not need a team of high-priced estate attorneys to execute brilliant tax-advantaged wealth transfers today. Here are the three most powerful annual maneuvers available to any household:
1. Direct Tuition and Medical Payments (The Unlimited Exclusion)
Under federal tax rules, you can pay an unlimited amount of tuition or medical expenses for anyone, your child, grandchild, niece, nephew, or friend, completely free of gift tax. The only rule is that you must pay the educational institution or medical healthcare provider directly. It does not count toward your $19,000 annual exclusion and does not reduce your lifetime exemption by a single penny.
2. Gifting Appreciated Stock Instead of Cash
If you plan to give money to an adult child who is in a low tax bracket (e.g., in college or starting their career), do not sell stock to give them cash. Gift the appreciated shares directly, whether that is vested company stock or core holdings from our Recommended Investments Guide (or download the Low-Cost Index Funds Cheat Sheet PDF). If their taxable income is under the 0% Long-Term Capital GainsProfits earned from selling assets you owned for longer than one year, which are taxed at preferential rates (0%, 15%, or 20%) rather than standard paycheck income tax rates. threshold (up to $48,350 single or $96,700 married in 2026), they can sell the shares at a 0.0% federal tax rate, completely wiping out your built-in capital gains. You can also check if your portfolio has hidden redundancy before gifting using our ETF Overlap & Concentration Screener.
For charitable giving, donating highly appreciated stock directly to a Donor-Advised Fund (DAF) gives you an immediate itemized deduction for the full fair market value, erases the capital gains tax completely, and shrinks your taxable estate without the cost of setting up a private foundation.
3. 529-to-Roth Rollovers for Excess College Savings
If you overfunded a child's 529 plan, you no longer face the dreaded 10% tax penalty on unused funds. Under modern SECURE 2.0 rules, beneficiaries can roll over up to $35,000 of leftover 529 funds into their own personal Roth IRA over their lifetime. Read our comprehensive 529-to-Roth Rollover Rules Guide for complete timing details.
Summary Checklist & What to Do Next
True financial wisdom is not about implementing the most complicated legal paperwork possible. It is about matching the right tool to your actual balance sheet.
If your household is under $5M, celebrate: you have full liquidity, complete control, and zero federal estate tax liability. Keep your living trust fully funded, update your beneficiary designations, and maximize your family's annual gifting and investment accounts. As your net worth crosses $10M and $15M, introduce growth-freezing structures deliberately with a trusted, fiduciary estate attorney.
For a complete breakdown of when and how to introduce these concepts to your family, review our new companion guide: The Complete Kids Money Milestones Timeline (Ages 3 to 18+).
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Frequently Asked Questions
Quick answers to common questions, technical edge cases, and tax rules.
What is the difference between a revocable living trust and an irrevocable trust?
A revocable living trust can be modified or dissolved at any time while you are alive, allowing you to maintain full control of your assets while avoiding public probate court at death. An irrevocable trust permanently removes assets from your personal ownership and control, which provides estate tax reduction and creditor protection but cannot be altered without court or beneficiary consent.
Why would someone with $15M consider irrevocable trusts if the married federal exemption is around $30M?
Compounding investment growth will easily push a $15M portfolio past the $30M federal exemption over a 15 to 25 year retirement horizon. A $15M portfolio growing at a 7% nominal annual return reaches $29.5M in 10 years and over $58M in 20 years, making growth-freezing strategies like SLATs and GRATs necessary decades before death to prevent 40% federal estate taxes on future appreciation.
How does a SLAT remove assets from a joint estate while still allowing a spouse access?
A SLAT removes assets from your taxable estate through a completed gift using your lifetime exemption. Because the beneficiary spouse only has a limited right to distributions for health, maintenance, and support rather than unrestricted ownership, tax rules exclude the trust from both spouses' gross estates while still allowing the beneficiary spouse to receive spending distributions.
What is a dynasty trust and why do wealthy families use them?
A dynasty trust is an irrevocable trust created in a state without time limits (such as South Dakota or Nevada) that holds assets across multiple generations. By applying generation-skipping transfer tax exemptions, the family's assets compound indefinitely without paying the 40% federal estate tax at each generation's death.
What is a Grantor Retained Annuity Trust (GRAT) in simple terms?
A GRAT is a financial container where you transfer high-growth assets for a set number of years, receive an annual annuity payment equal to your original principal plus an official IRS interest rate, and pass all excess appreciation above that benchmark to your children completely gift-tax-free.
How does annual exclusion gifting work without triggering taxes?
Under the annual gift tax exclusion, any individual can gift up to $19,000 per recipient per calendar year to an unlimited number of people without filing a gift tax return or tapping their lifetime exemption. A married couple can combine their exclusions to give up to $38,000 per child, grandchild, or relative each year completely tax-free.
What is 529 college plan 5-year superfunding?
Superfunding allows a parent or grandparent to front-load five years worth of annual gift tax exclusions into a single 529 college savings contribution in year one. A married couple can contribute up to $190,000 per child in a single deposit by filing IRS Form 709, immediately moving those funds out of their taxable estate while generating decades of tax-free educational growth.
Download the Generational Wealth & Minor Account Setup Checklist
A one-page educational checklist on custodial accounts, 529 plans, and passing wealth to the next generation.
- ✓ Account types for minors compared
- ✓ Setup steps and common pitfalls
- ✓ Questions to bring to an advisor
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this reference handy for future planning!
Your Next Step & Related Guides
View all resources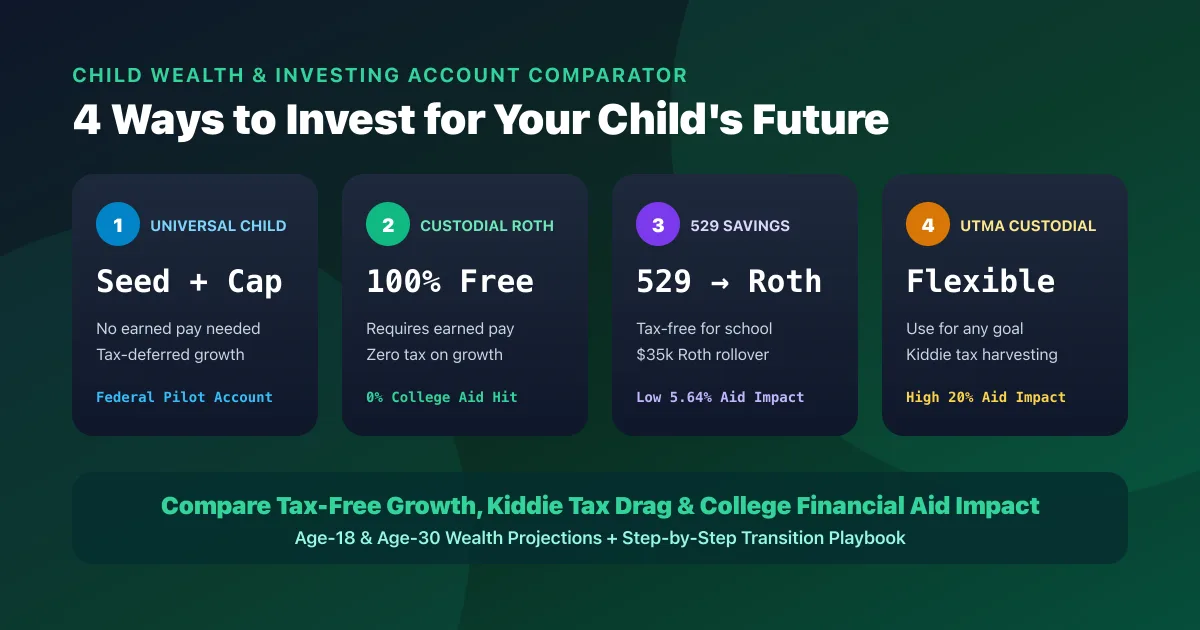
Child Account Comparator
See projected outcomes across 529, UTMA, and custodial Roth accounts.
5 Ways To Pass Down Generational Wealth Tax-Free
If you happen to be in a financial position where you’re planning to pass down generational wealth, congratulations! You’re in a great situation, compared to the bottom ⅔ of Americ
How the Rich Create Generational Wealth Through Real Estate
Discover how the wealthy use 1031 exchanges, depreciation, and the step-up in basis to pass down real estate and build generational wealth tax-free.
Discussion 0
Author replies within 24h