
How to Build Your Kid's Credit Score Early
Listen to Full Article
ReadyFull article audio (4 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: How to Build Your Kid's Credit Score Early
I purchased my first home at age 22. While I had saved diligently, the approval came down to my credit profile. Because my parents added me as an authorized user early on, I had an established credit history that qualified me for tier-1 mortgage interest rates straight out of college.
Most young adults graduate college with zero credit history, forcing them into high-interest subprime auto loans or requiring cosigners for basic apartment leases. With proper planning, you can position your child to turn 18 with a 750+ credit score.
Card Issuer Authorized User Rules and Age Minimums
The fastest and most reliable way to establish credit for a minor is by adding them as an authorized user on an existing credit card account with flawless payment history and low utilization. Here is how major financial institutions handle authorized users for minors:
| Credit Card Issuer | Minimum Age for Authorized User | Reports Full Historical Account Age? | Requires Minor SSN? |
|---|---|---|---|
| American Express | 13 years old | No (reports only from addition date) | Yes (within 60 days) |
| Chase | No minimum age | Yes (full account history inherited) | No (SSN optional) |
| Capital One | No minimum age | Yes (full account history inherited) | Yes |
| Discover | 15 years old | Yes (full account history inherited) | Yes |
| Citi | No minimum age | Yes (full account history inherited) | No (Date of birth required) |
| Bank of America | No minimum age | Yes (full account history inherited) | Yes |
The Anatomy of a Credit Score for Teens
When the credit bureaus compile your child's credit file at age 18, FICO scoring models evaluate five primary pillars:
Payment History (35%): A single 30-day late payment can drop a credit score by 80 to 100 points. Only add your child to accounts with a 100% on-time payment track record.
Amounts Owed / Credit Utilization (30%): Total revolving balances divided by total credit limits. Aim to keep utilization below 10% across all statement closing dates.
Length of Credit History (15%): Average age of accounts. Issuers that report the entire account history give your child an instant 5- to 10-year account vintage upon turning 18.
New Credit (10%): Hard credit inquiries. Authorized user additions do not trigger hard inquiries on your child's report.
Credit Mix (10%): Managing revolving credit cards alongside installment loans (such as college student loans or auto financing).
Best Practices: Protect Your Child and Your Credit
You Do Not Need to Hand Over the Card: When the secondary card arrives in the mail, you can safely store it in a home safe or destroy it. The credit bureau reporting occurs independently of whether the physical card is swiped.
Choose Cards with Seasoned History: Select an account that has been open for at least 5 years with a large credit line ($10,000+) and zero late payments.
Pair Credit Access with Financial Literacy: Credit building without spending discipline creates vulnerability. As teens approach college age, introduce debit card budgeting and teach how compounding interest works against revolving debt.
To compare account options for a child, try the Child Account Comparator or the Living Trust Funding Checklist.
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Frequently Asked Questions
Quick answers to common questions, technical edge cases, and tax rules.
Can a minor have a credit score before turning 18?
Credit bureaus generally do not generate public credit scores for individuals under age 18. However, authorized user data accumulates in the background and populates into a score the moment they turn 18.
What happens if the parent carries a high balance or misses a payment?
Negative account actions report directly to the authorized user's credit profile as well. If payment problems arise, parents can remove the child as an authorized user, which typically deletes the entire account tradeline from the child's file.
Does adding an authorized user affect the parent's credit score?
No. Adding an authorized user does not generate a hard inquiry on the primary cardholder or affect their score, provided card utilization remains low.
Download the Generational Wealth & Minor Account Setup Checklist
A one-page educational checklist on custodial accounts, 529 plans, and passing wealth to the next generation.
- ✓ Account types for minors compared
- ✓ Setup steps and common pitfalls
- ✓ Questions to bring to an advisor
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this reference handy for future planning!
Your Next Step & Related Guides
View all resources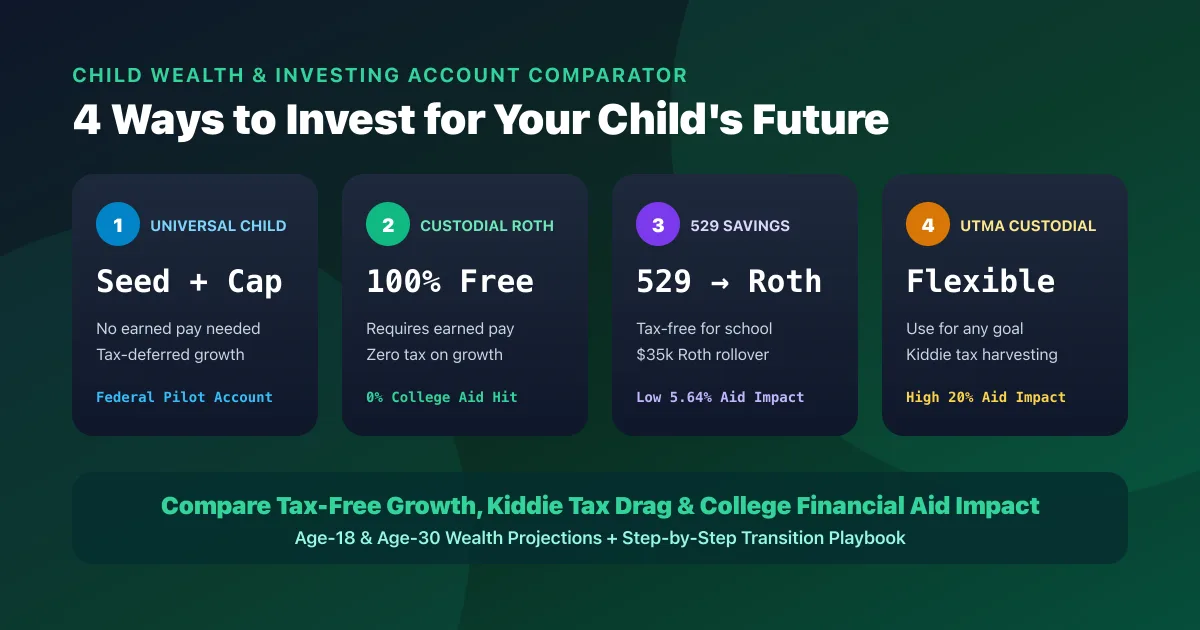
Child Account Comparator
See projected outcomes across 529, UTMA, and custodial Roth accounts.
Bad Debt, Better Debt
Okay, you made a mistake of carrying your credit card balance over one month. So what? It’s just a month. Next, you continued to carry that balance over one more month. No problem,
My 2025 Spending Review
A transparent 2025 spending review breaking down real credit card expenses by category and rewards earned, with zero housing costs included.
Discussion 🟢 Open for Discussion 0