How the 529-to-Roth IRA Rollover Works
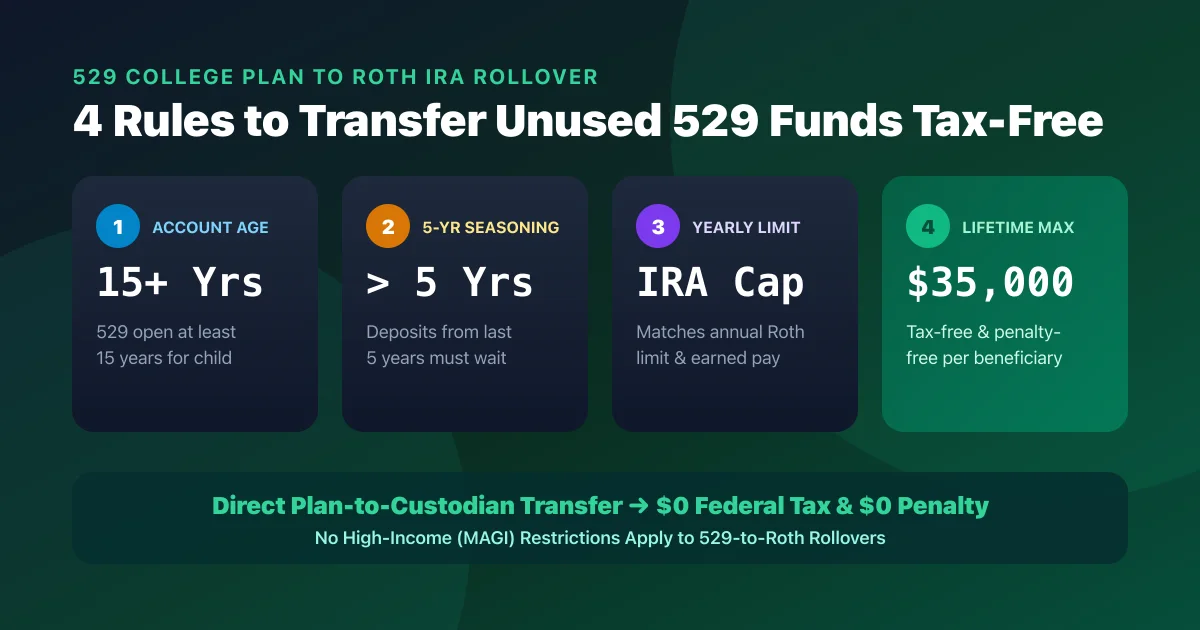
Thanks to the SECURE 2.0 Act, you can transfer up to $35,000 of unused 529 college funds directly into a Roth IRA for the account's beneficiary with zero federal income tax and zero penalty. To qualify, the 529 plan must have been open for at least 15 years, any money deposited within the last 5 years (plus its investment growth) must stay in the account until it turns 5 years old, and each year's transfer is capped at the annual Roth IRA contribution limit ($7,500 in 2026 for beneficiaries under age 50, or $8,600 for age 50+), up to the beneficiary's earned income. Best of all, normal Roth IRA high-income limits do not apply.
The 4 Plain-English Rules for a Tax-Free Rollover
Before Congress passed the SECURE 2.0 Act (Internal Revenue Code Section 529 and IRS Notice 2024-02), parents who saved too much in a 529 plan faced an expensive dilemma: if their child received a scholarship, attended a lower-cost school, or skipped college, taking leftover money out for non-school expenses triggered ordinary income taxes plus a 10% penalty on the investment gains.
The 529-to-Roth IRA rollover solves the "overfunded 529" problem by letting your child jump-start their tax-free retirement portfolio, provided you follow four straightforward rules:
- 1. The 15-Year Account Age Rule: The 529 account must have been open for at least 15 full years (180 months) before you initiate a rollover.
- 2. The 5-Year Deposit Seasoning Rule: You cannot open or stuff a 529 account right before graduation and immediately roll it into a Roth IRA. Any unseasoned contributions made within the last 5 years (and the investment growth earned on those recent deposits) must wait until their 5-year anniversary passes.
- 3. The $7,500 Annual Cap & Earned Income Rule: In 2026, you can roll over up to $7,500 per year (the standard Roth IRA contribution limit). Two conditions apply:
- The beneficiary must have taxable earned income at least equal to the rollover amount (for example, if your child earns $5,000 at a summer job in 2026, their maximum rollover for 2026 is $5,000).
- The $7,500 limit is shared with regular Traditional and Roth IRA contributions. If your child contributes $2,500 of their own paycheck directly to a Roth IRA in 2026, only $5,000 can be rolled over from the 529 plan that year.
- 4. The $35,000 Lifetime Cap: A single beneficiary can receive up to $35,000 in total 529-to-Roth rollovers over their lifetime across all 529 accounts combined. At $7,500 per year, maxing out the full $35,000 takes 5 calendar years (4 years of $7,500 plus a final year of $5,000).
Does Changing the Beneficiary Reset the 15-Year Clock?
One of the most common questions parents ask is: "If my oldest child finishes college with $30,000 left in their 16-year-old 529 plan, can I change the beneficiary to my younger child (or to myself) and immediately roll the money into a Roth IRA?"
Because the federal statute states that the 529 account must have been maintained for the designated beneficiary for 15 years, major 529 plan administrators take a cautious stance while waiting for final IRS regulations:
| 529 Plan Provider | Beneficiary Change Policy | State-to-State 529 Transfer Policy | Rollover Request Method |
|---|---|---|---|
| Fidelity (MA U.Fund, NH UNIQUE, AZ, DE) | Conservative: Warns that changing the beneficiary may restart the 15-year clock; requires account owner sign-off. | Carries over original open date if you provide prior-plan statements. | Fidelity 529-to-Roth Direct Rollover Form |
| Vanguard (Nevada 529 & Ascensus Plans) | Strict: Advises owners that a new beneficiary designation restarts the 15-year waiting period until IRS rules otherwise. | Preserves original open date only when prior custodian sends historical breakdown. | Ascensus Qualified Rollover to Roth IRA Form |
| Utah my529 (Direct-Sold Plan) | Owner Certification: Processes the transfer upon owner signature, but flags IRS audit risk if the beneficiary changed <15 yrs ago. | Retains original open date for internal Utah account splits if same beneficiary. | my529 Form 215 (529 to Roth IRA Transfer) |
| NY 529 Direct Plan (Ascensus / Vanguard) | Federal Alignment: Follows federal 15-year rules for NY state tax conformity; flags beneficiary changes within 15 years. | Requires statement proof of original 529 account opening date. | NY 529 Roth IRA Direct Rollover Form |
Best Practice for Parents
How to Execute the Transfer & File Tax Forms (Form 1099-Q & Form 5498)
Every 529-to-Roth rollover must be completed as a direct trustee-to-trustee transfer. Do not withdraw the money to your personal checking account and deposit it into a Roth IRA yourself; an indirect withdrawal will be taxed and penalized as a non-qualified withdrawal.
- Step 1: Open a Roth IRA in the Beneficiary's Name: Confirm that the 529 beneficiary has an open Roth IRA at a brokerage like Fidelity, Vanguard, or Schwab. (If the beneficiary is a minor with earned income, open a Custodial Roth IRA for Kids).
- Step 2: Submit the 529 Plan's Direct Rollover Form: Provide the receiving Roth IRA account number and custodian routing details on your 529 plan's "Qualified Rollover to Roth IRA" form. Tip: You have until the April tax filing deadline (April 15) to complete a 529-to-Roth rollover designated for the prior tax year, provided both custodians support prior-year coding.
- Step 3: Reconcile IRS Form 1099-Q & IRS Form 5498: The following January, your 529 plan will issue Form 1099-Q showing the total distribution in Box 1, earnings in Box 2, original deposits (basis) in Box 3, and a checkmark in Box 4 confirming a direct trustee-to-trustee transfer. Your Roth IRA brokerage will report the incoming transfer in Box 10 of Form 5498.
- Step 4: Check Your State's Tax Conformity: While the rollover is 100% tax-free on your federal return, a few states (most notably California, which imposes a 2.5% state penalty on non-qualified 529 earnings, and certain states that claw back prior state 529 tax deductions) have not aligned their state tax laws with the federal SECURE 2.0 rule. Check your state 529 plan disclosure before initiating the transfer.
Combining 529 Rollovers with Backdoor & Mega Backdoor Roth Accounts
For high earners and recent graduates starting high-paying careers, the 529-to-Roth rollover unlocks powerful tax planning opportunities:
- Bypasses High-Income Roth IRA Limits (MAGI): Normally, once your income exceeds the federal Roth IRA ceiling, you cannot contribute directly to a Roth IRA and must use a Backdoor Roth IRA with Fidelity. A 529-to-Roth rollover completely ignores the income ceiling. However, because it uses the same $7,500 annual IRA bucket, you cannot do both a $7,500 529 rollover and a $7,500 Backdoor Roth IRA in the same tax year.
- Stacks 100% on Top of Your 401(k) & Mega Backdoor Roth: Your $7,500 IRA limit is completely separate from your workplace 401(k) limit ($24,000 employee deferral and $71,000 total 401(k) cap in 2026). That means a graduate can receive a $7,500 529-to-Roth IRA rollover while simultaneously maxing out their 401(k) and executing a Mega Backdoor Roth 401(k) with Fidelity. Model your workplace contribution room in our Mega Backdoor Roth Calculator and check our 401(k) Benefits & Mega Backdoor Employer Directory.
 Buck by Buck
Discussion 0
Questions, thoughts, or experience to share on 529 to Roth IRA Rollover Rules & Calculator? Join the conversation below.