
Comparing Cash vs Leveraged Real Estate Investing
Listen to Full Article
ReadyFull article audio (3 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: Comparing Cash vs Leveraged Real Estate Investing
In real estate investing, few debates are as hotly contested as all-cash purchasing versus mortgage leverage. Advocates of all-cash highlight guaranteed debt-free cash flow and sleep-well-at-night security. Proponents of leverage emphasize the compounding power of mortgage AmortizationThe schedule showing how your regular mortgage payments are divided between paying down actual debt principal versus interest over time., inflation hedging, and multiplying asset appreciation.
To evaluate which approach creates greater long-term wealth, let's examine a live case study comparing a debt-free $1,000,000 fourplex against two 50% mortgaged fourplexes using real-world numbers and current interest rates.
Side-by-Side Comparison: Cash vs Leveraged Fourplex
| Financial Metric | Option 1: One Fourplex (100% Cash) | Option 2: Two Fourplexes (50% Mortgaged) |
|---|---|---|
| Total Capital Invested | $1,000,000 equity | $1,000,000 equity ($500K per building) |
| Total Asset Value Controlled | $1,000,000 (4 units) | $2,000,000 (8 units) |
| Gross Monthly Rent ($2,200/unit) | $8,800/mo | $17,600/mo |
| Operating Expenses (Taxes, Ins, Vacancy) | -$2,945/mo | -$5,890/mo |
| Monthly Debt Service (6.125% Rate) | $0 | -$6,076/mo ($3,038 per loan) |
| Net Monthly Pre-Tax Cash Flow | $5,855/mo | $5,634/mo |
| Annual Net Pre-Tax Cash Flow | $70,260/yr | $67,608/yr |
| Cash-on-Cash Return | 7.13% | 6.76% |
| Annual Principal Paydown (Year 1) | $0 | +$12,400 equity buildup |
| Annual 3% Asset Appreciation | +$30,000 | +$60,000 |
| Total Net Annual Return (Cash + Principal + Appr) | $100,260 (10.0% Total ROI) | $140,008 (14.0% Total ROI) |
Cash Flow vs Total Wealth Accumulation
When evaluated strictly on immediate monthly cash flow, the all-cash fourplex edges out the two leveraged properties by $2,652 per year ($70,260 vs $67,608). In a high-interest-rate environment where commercial mortgage rates exceed 6%, debt service significantly reduces operational cash flow margins.
However, focusing exclusively on cash flow ignores the other wealth generators unique to leveraged real estate:
Tenant Amortization: The tenants in the two leveraged fourplexes pay down over $12,400 in principal in the first year alone, compounding higher each subsequent year.
Appreciation Multiplier: A modest 3% annual appreciation on $1,000,000 of real estate produces $30,000 in equity growth. That same 3% appreciation on $2,000,000 of real estate generates $60,000, doubling your equity accumulation on the identical $1M cash outlay.
Double the Tax Depreciation: Controlling two buildings provides twice the depreciable basis, shielding substantially more rental income from federal and state income taxes.
To analyze potential investment returns on your target properties, test out our free Real Estate Evaluation Tool, or explore our case study on triple-net leaseback investing lessons.
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Frequently Asked Questions
Quick answers to common questions, technical edge cases, and tax rules.
Is it safer to buy investment property with all cash?
Buying with all cash eliminates mortgage foreclosure risk and ensures maximum monthly cash flow during vacancies. However, it concentrates capital into fewer assets and forfeits the compounding leverage of mortgage principal paydown and tax depreciation.
How does leverage increase real estate return on equity?
Leverage increases return on equity by allowing an investor to control a larger asset base with a smaller down payment. Appreciation and loan amortization apply to the full purchase price of the property, not just the investor's down payment.
When should an investor choose all-cash over leverage?
All-cash is ideal for retirees prioritizing risk-free passive cash flow over capital growth, or when prevailing mortgage interest rates exceed the capitalization rate of the target property (negative leverage).
Download the Homeowner Wealth & Mortgage Optimization Playbook
A one-page educational reference on home equity, mortgage decisions, and rent-versus-buy considerations.
- ✓ Rent versus buy considerations
- ✓ Mortgage payoff and recast concepts
- ✓ Home equity and opportunity cost notes
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this reference handy for future planning!
Your Next Step & Related Guides
View all resources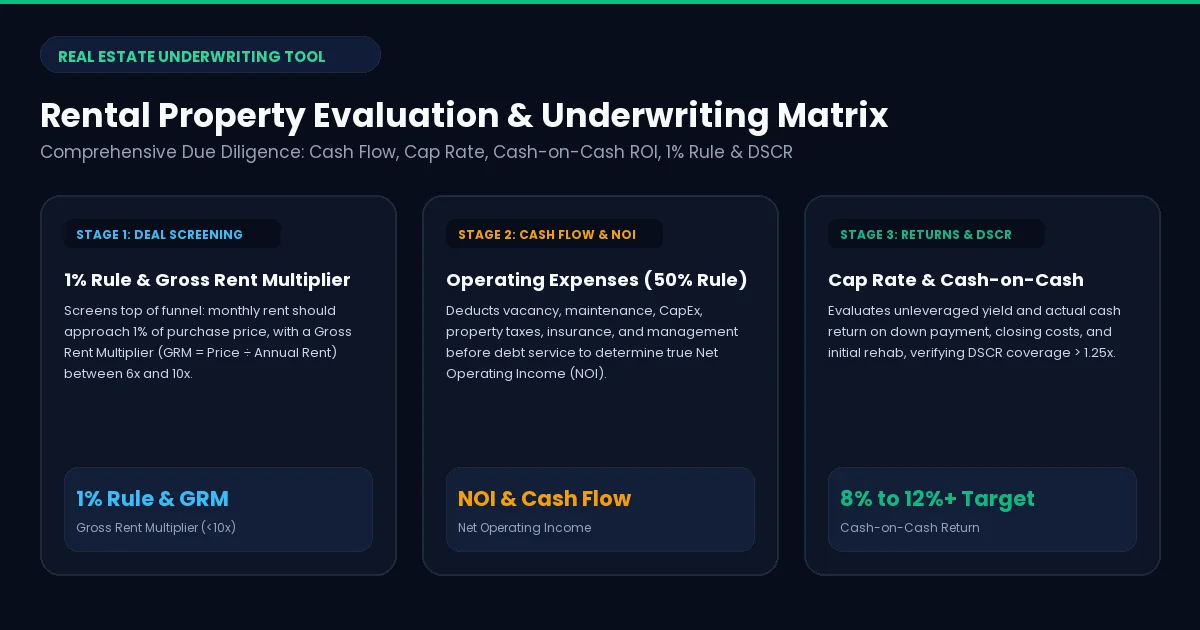
Real Estate Evaluation Tool
Screen rental properties with cash-on-cash return and cap rate.
Investing in Fourplexes 10 Years Apart
Don't wait for "perfect" deals from a decade ago. Learn why lowering expectations and understanding today's interest rates are key to pulling the trigger on your next investment.
Investing in a Pre-Construction Fourplex
A step-by-step look at pre-construction fourplex investing, from contract to completion, with costs, timelines, and expected rental setup.
Discussion 🟢 Open for Discussion 0