Mega vs Regular Backdoor Roth: What's the Difference?
Listen to Full Article
ReadyFull article audio (6 min) • Click to listen from start to finish
Read Selection (0 words)
"..."
Ch: Mega vs Regular Backdoor Roth: What's the Difference?
For high income earners, the Backdoor Roth conversion is a popular way to get around the income limits that prevent high earners from contributing directly to a Roth IRA. The Mega Backdoor Roth, on the other hand, is not just for high earners. However, a high income is necessary in order to get close to contributing up to the maximum, which is probably why they put “Mega” in the name. In this article, I will talk about the differences between the two backdoor conversions so that you can decide which one is right for you.
A Quick Refresher
Before we talk about the differences between the Mega and regular Backdoor Roths, I want to briefly go over a few terms you’ll need to know.
Roth. If a retirement account has “Roth” in the name, that means that account has post-tax dollars in it and the earnings grow tax-free. So both the Roth 401(k) and Roth IRA share these qualities.
IRA. If a retirement account has “IRA” in the name, that means the account is opened and controlled entirely by you, not by an employer. The 2026 max contribution limit is $7,500 (under 50) and $8,600 (50+). If you contribute $3,000 to a Traditional IRA and $4,500 to a Roth IRA in 2026, you’ve reached the annual limit.
401(k). If a retirement account has “401(k)” in the name, that means the account is run through your employer. While you control how much money you invest in it and which fund(s) to invest in, your employer determines which fund(s) are available to you. The 2026 max contribution limit is $24,500 (under 50). For example, if you contribute $14,500 pre-tax dollars into a traditional 401(k) and $10,000 post-tax dollars into a Roth 401(k), you’ve reached the annual limit.
Employer match. As a company perk, some employers offer a match program where they contribute money to your 401(k). Basically free money. Typically, you’ll have to contribute a certain amount yourself, and employers will only match up to a certain dollar amount or percentage of your gross income. The employer contributions into your 401(k) do not count towards the annual $24,500 contribution limit. Instead, there’s actually a higher, combined employee + employer limit of $72,000 for 2026. For example, if you contribute $24,500 and your employer contributes $5,500, combined, you’ve used up $30,000 out of the combined $72,000 limit.
Mega vs Regular Backdoor Roth
The goal of the regular Backdoor Roth conversion is to work around the income limits that prevent high earners from contributing directly to a Roth IRA. For example, if you have an income between $153K and $168K, you are only allowed to contribute a fraction of the typical $7,500 maximum (available to single filers who make less than $153K per year). And if you recall from the definitions above, IRAs are opened and managed by you, not an employer. IRAs really have nothing to do with your 401(k)s.
The Mega Backdoor RothA strategy that lets you supercharge your retirement savings by putting after-tax dollars into your employer 401(k) beyond the standard limit, then rolling them into a Roth 401(k) or Roth IRA., on the other hand, is a (rare) benefit offered by employers. In order to be able to do a Mega Backdoor Roth IRAA simple two-step workaround for high earners who make too much to contribute to a Roth IRA directly: you deposit after-tax cash into a Traditional IRA and immediately convert it to a Roth IRA., your employer needs to allow for after-tax contributions into your Traditional 401(k). Many employers don’t. But if yours does, you’re in luck!
| Backdoor Roth | Mega Backdoor Roth | |
|---|---|---|
| Requirements | None. You can do this yourself. | Your employer needs to offer after-tax contributions into your Traditional 401(k). |
| Contribution Limit | $7,500 or $8,600 (age 50+) | Less than or equal to $47,500 |
| Suggested Income Level | $153K and above (single) or $242K and above (married) | Any income level. But you need to make sure you leave enough paycheck for your expenses. |
| Complexity | Low-to-medium | High |
| Interactive Tools | Roth Ladder Calculator | Mega Backdoor Calculator |
| Where To Learn More | Step-by-step guide | Step-by-step guide |
Only high earners will want to utilize the Backdoor Roth conversion. Why? Because going through the motions takes several extra steps compared to simply contributing directly to a Roth IRA. If you don’t make $153K (single) or $242K (married) in 2026, you might as well stick with the regular Roth IRA. Don’t bother with a Backdoor Roth conversion.
Takeaways
Both Backdoor conversions have a place in the personal finance playbook, but be sure to consider the complexities, tax consequences, and your income level before choosing which to utilize. If your plan supports after-tax contributions, you can use our Mega Backdoor Roth Calculator to project your contributions, model early retirement withdrawals with the Roth Conversion Ladder Calculator, or see how to combine conversions with basis recovery in our 0% Tax Early Retirement Blueprint.
Aside: For those of you who’ve been wondering why I haven’t been actively publishing blog posts or Instagram posts, I have taken some well-deserved vacations and I’ve been working on some new and exciting things! Stay tuned for some coming announcements between now and the rest of the year!
Scan to Open on Phone
Point your phone's camera at the QR code to seamlessly continue reading or calculate with your current inputs on mobile.
 Buck by Buck
No app required
Bookmark this page
Press ⌘+D or Ctrl+D to save to your browser bookmarks.
Download the Executive Equity & Tax Optimization Playbook
A one-page educational reference covering equity compensation, retirement accounts, and tax-aware planning concepts.
- ✓ Equity compensation tax basics
- ✓ Account-type and bracket considerations
- ✓ Questions to bring to a tax professional
Your PDF is Ready!
Click below to download or save your printable companion guide:
We also sent a backup copy to your email. Keep this checklist handy for retirement and tax planning!
Your Next Step & Related Guides
View all resources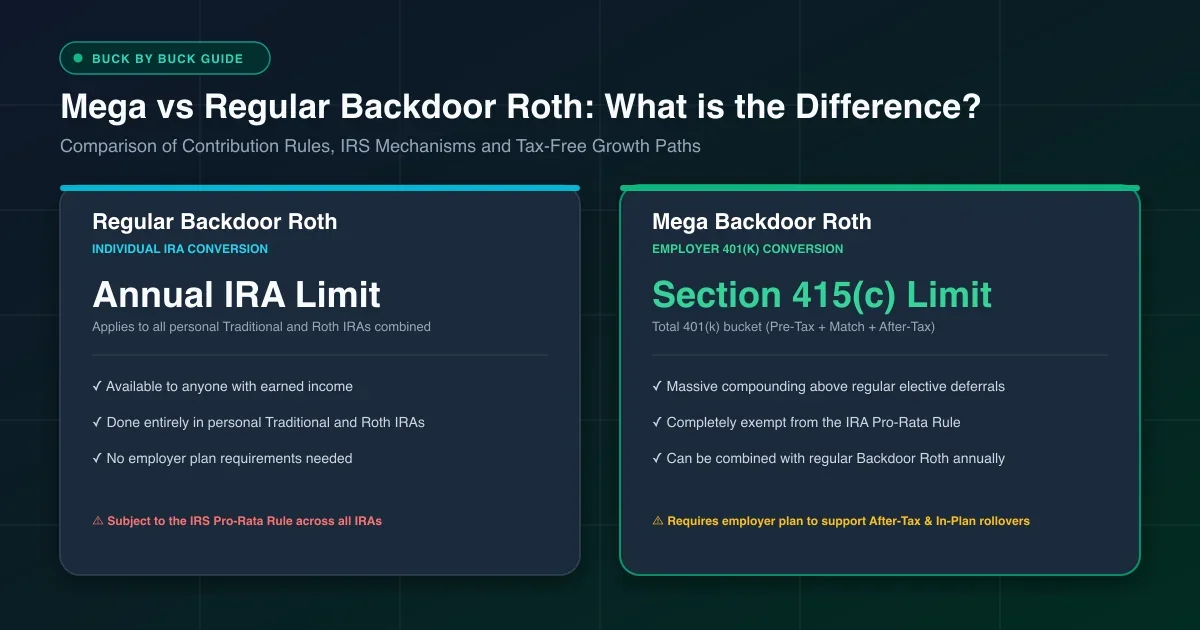
Mega Backdoor Roth Calculator
Estimate your remaining after-tax 401(k) contribution space.
What's A Mega Backdoor Roth?
If you like your Roth IRA for its tax-free growth, you’re really going to like a mega backdoor Roth! Contributions to a Roth IRA are funded with after-tax dollars and earnings grow
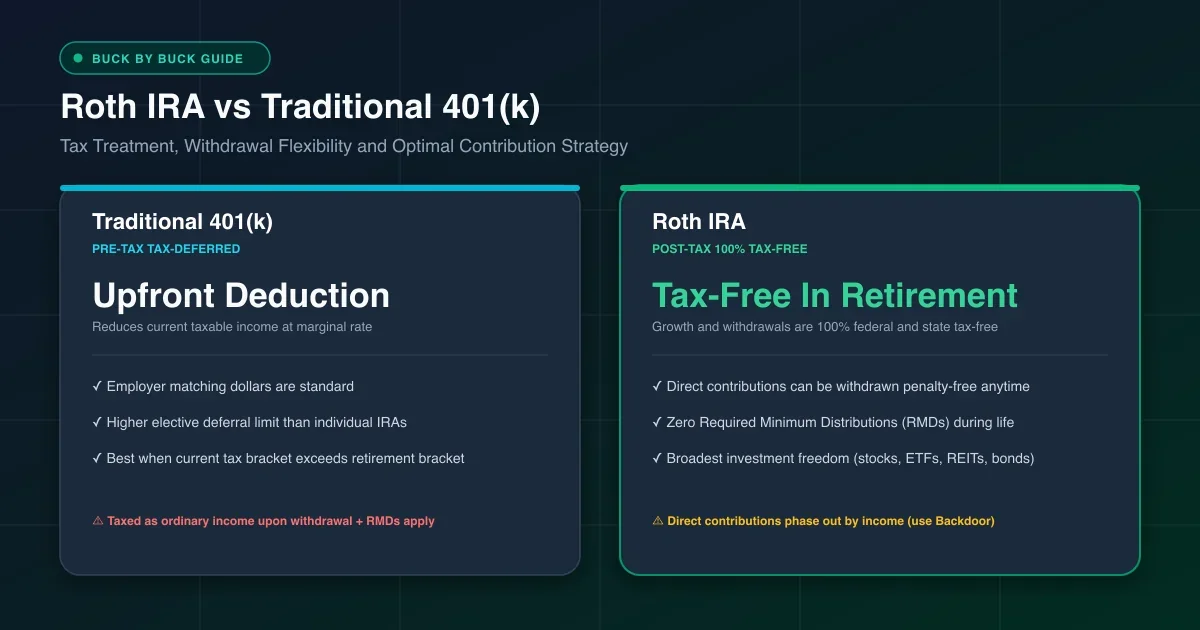
Roth IRA or 401(k): Which One Is Right For You?
I hear it all the time, “Should I invest in a Roth IRA or a 401(k)?” To help you answer that question, first we need to know what they are and what some of their benefits are. From
Discussion 🟢 Open for Discussion 0